Welcome to the Blog
Keep up with the latest news and updates
Check out Pam in Voyage Denver Magazine.
http://voyagedenver.com/interview/meet-pamela-maass-maass-law-littleton/
Pam Featured in Voyage Denver Magazine
If you’re planning to leave your children an inheritance of any amount, you likely want to do everything you can to protect what you leave behind from being lost or squandered. While most lawyers will advise you to distribute the assets you’re leaving to your kids outright at specific ages and stages, based on when you think they will be mature enough to handle an inheritance, there is a much better choice for safeguarding your family wealth.A Lifetime Asset Protection Trust is a unique estate planning vehicle that’s specifically designed to protect your children’s inheritance from unfortunate life events such as divorce, debt, illness, and accidents. At the same time, you can give your children the ability to access and invest their inheritance, while retaining airtight asset protection for their entire lives.Last week, we discussed how Lifetime Asset Protection Trusts differ from the standard way that most revocable living trusts and wills distribute assets to beneficiaries. Today, we’ll look at the Trustee’s role in the process and how these unique trusts can teach your kids to manage and grow their inheritance, so it can support your children to become wealth creators and enrich future generations.
Total discretion for the Trustee offers airtight asset protection
As mentioned last week, most trusts require the Trustee to distribute assets to beneficiaries in a structured way, such as at certain ages or stages. Other times, a Trustee is required to distribute assets only for specific purposes, such as for the beneficiary’s “health, education, maintenance, and support,” also known as the “HEMS” standard. In contrast, a Lifetime Asset Protection Trust gives the Trustee full discretion on whether to make distributions or not. The Trust leaves the decision of whether to release trust assets totally up to the Trustee. The Trustee has full authority to determine how and when the assets should be released based on the beneficiary’s needs and the circumstances going on in his or her life at the time.For example, if your child was in the process of getting divorced or in the middle of a lawsuit, the Trustee would refuse to distribute any funds. Therefore, the Trust assets remain shielded from a future ex-spouse or a potential judgment creditor, should your child be ordered to pay damages resulting from a lawsuit.
What’s more, because the Trustee controls access to the inheritance, those assets are not only protected from outside threats like ex-spouses and creditors, but from your child’s own poor judgment, as well. For example, if your child develops a substance abuse or gambling problem, the Trustee could withhold distributions until he or she receives the appropriate treatment.
A lifetime of guidance and support
Given that distributions from a Lifetime Asset Protection Trust are 100% up to the Trustee, you may be concerned about the Trustee’s ability to know when to make distributions to your child and when to withhold them. Granting such power is vital for asset protection, but it also puts a lot of pressure on the Trustee, and you probably don’t want your named Trustee making these decisions in a vacuum.
To address this issue, you can write up guidelines to the Trustee, providing the Trustee with direction about how you’d like the trust assets to be used for your beneficiaries. This ensures the Trustee is aware of your values and wishes when making distributions, rather than simply guessing what you would’ve wanted, which often leads to problems down the road. In fact, many of our clients add guidelines describing how they’d choose to make distributions in up to 10 different scenarios. These scenarios might involve the purchase of a home, a wedding, the start of a business, and/or travel. Some clients choose to provide guidelines around how they would make investment decisions, as well. This is something we can support you with if you decide to use a Lifetime Asset Protection Trust.
An educational opportunity
Beyond these benefits, a Lifetime Asset Protection Trust can also be set up to give your child hands-on experience managing financial matters, like investing, running a business, and charitable giving. And he or she will learn how to do these things with support from the Trustee you’ve chosen to guide them.This is accomplished by adding provisions to the trust that allow your child to become a Co-Trustee at a predetermined age. Serving alongside the original Trustee, your child will have the opportunity to invest and manage the trust assets under the supervision and tutelage of a trusted mentor. You can even allow your child to become Sole Trustee later in life, once he or she has gained enough experience and is ready to take full control. As Sole Trustee, your child would be able to resign and replace themselves with an independent trustee, if necessary, for continued asset protection.
Future generations
Regardless of whether or not your child becomes Co-Trustee or Sole Trustee, a Lifetime Asset Protection Trust gives you the opportunity to turn your child’s inheritance into a teaching tool. Do you want to give your child the ability to leave trust assets to a surviving spouse or a charity upon their death? Or would you prefer that the assets are only distributed to his or her biological or adopted children? You might even want your child to create their own Lifetime Asset Protection Trust for their heirs.We offer you a wide variety of options that can be tailored to fit your particular values and family dynamics. Be sure to ask us which options might be best for your particular situation.
Is a Lifetime Asset Protection Trust right for you?
Of course, Lifetime Asset Protection Trusts aren’t for everyone. If your kids are going to spend the vast majority of their inheritance on everyday expenses and consumables, they probably don’t make much sense. But if you want the assets you are leaving behind to be invested and grown over the long term, a Lifetime Asset Protection Trust can be immensely valuable.
Meet with us to see if a Lifetime Asset Protection Trust is the right option for your family. In the end, it’s not about how much you’re leaving your loved ones that matters. It’s about ensuring that what you do pass on is there when it’s needed most and put to the best use possible. Schedule a Family Wealth Planning Session today to learn more.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Family Wealth Planning Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
Lifetime Asset Protection Trusts: Airtight Asset Protection For Your Child’s Inheritance—Part 2
As a parent, you’re likely hoping to leave your children an inheritance. In fact, doing so may be one of the motivating factors driving your life’s work. But without taking the proper precautions, the wealth you pass on is at serious risk of being accidentally lost or squandered. In some instances, an inheritance can even wind up doing your kids more harm than good. Creating a will or a revocable living trust offers some protection, but in most cases, you’ll be guided to distribute assets through your will or trust to your children at specific ages and stages, such as one-third at age 25, half the balance at 30, and the rest at 35. If you’ve created estate planning documents, check to see if this is how your will or trust leaves assets to your children. If so, you may not have been told about another option that can give your children access, control, and airtight asset protection for whatever assets they inherit from you.
In our planning process, we always offer parents the option of creating a Lifetime Asset Protection Trust for your children’s inheritance. A Lifetime Asset Protection Trust safeguards the inheritance from being lost to common life events, such as divorce, serious illness, lawsuits, or even bankruptcy. But that’s not all they do.Indeed, the best part of these trusts is that they offer you—and your kids—the best of both worlds: airtight asset protection AND use and control of the inheritance. What’s more, you can even use the trust to incentivize your children to invest and grow their inheritance.
Not just for the uber rich
Contrary to what you might think, Lifetime Asset Protection Trusts are not just for the super wealthy. Indeed, these protective trusts are even more useful if you’re leaving a relatively modest inheritance because they can be used to educate your children about how to grow your family wealth, instead of quickly blowing through it. And without such guidance, most people blow through their inheritance very quickly. In fact, one study found that, on average, an inheritance is totally gone in about five years due to debt and poor investment. Another study found that one-third of people who receive an inheritance actually had a negative savings within just two years.Not to mention, the smaller the inheritance, the more at risk it is of getting wiped out by a single unfortunate event like a medical emergency. Regardless of how much financial wealth you have (or don’t have), if you plan to leave your kids anything at all, you should do everything you can to make it more likely that they grow what’s left behind, instead of losing it. This way, your resources can have a truly beneficial effect on their lives—and even the lives of future generations. A Lifetime Asset Protection Trust can achieve each of those goals and so much more.
Not all trusts are created equal
Most lawyers will advise you to put the assets you’re leaving your kids in a revocable living trust—and this is the right move. But as mentioned earlier, most lawyers would structure the trust to distribute those assets outright to your children at certain ages or stages. And if you’ve used an online do-it-yourself will or trust-preparation service like LegalZoom®, Rocket Lawyer,® or any of the newer options frequently coming online now, you will most likely be offered only two options: outright distribution of the entire inheritance to your kids when you die, or partial distributions when they reach specific ages and stages as described above.Either of those options leaves their inheritance—and your hard-earned and well-saved money—at risk. Indeed, once assets pass into your child’s name, all of the protection previously offered by your trust disappears.
For example, say your son racked up debt while in college, which can sometimes happen. If he were to receive one-third of his inheritance at age 25, creditors could take his inheritance if it’s paid to him in an outright distribution.
The same thing would be true if your daughter gets a divorce after receiving her inheritance, only it would be her soon-to-be ex-spouse who would claim a right to the funds in a divorce settlement. And despite what you may have heard about an inheritance remaining separate property, once it’s in your child’s hands, outright and unprotected, those assets are at risk.
There’s just no way to foresee what the future has in store for your kids—these kind of events happen to families every day. And that’s not even taking into consideration that your kids might simply blow through the money and spend it all on unnecessary luxuries.
Airtight asset protection—and easy access
Lifetime Asset Protection Trusts are specifically designed to prevent your hard-earned assets from being wiped out by such risks. And at the same time, your children will still be able to use and invest the funds held in trust as needed. For example, even though the assets are held in trust, your kids would be able to invest those funds in things like stocks, a business, or real estate, provided they do so in the name of the trust. Plus, if your child needs to pull money out to pay for college, a new home, or medical bills, they can do that by asking a Trustee—who’s chosen by you to oversee the money—for a distribution. Or, as will cover next week, you may even allow your child to become Sole Trustee at some point in the future, allowing him or her to make decisions about the trust’s management.Obviously, creating a trust like this requires significant understanding of how to properly draft the trust, so don’t attempt to do create one without our guidance. And as you’ll see next week, Lifetime Asset Protection Trusts offer additional benefits that can be used to teach your kids how to invest and grow their inheritance, so that the assets you leave behind can be passed on to their children and beyond.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Family Wealth Planning Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.

Lifetime Asset Protection Trusts: Airtight Asset Protection For Your Child’s Inheritance—Part 1
Following the death of the policy holder, the way in which proceeds from a life insurance policy are paid to the beneficiary (or beneficiaries) is known as the settlement option. And you might be surprised to learn that there are a variety of settlement options available besides the most common method—a lump-sum payout. Depending on the life insurance company and policy, these options may be selected by the policy holder ahead of time or chosen by the beneficiary upon the insured’s death. Whether you’re the policy holder or beneficiary, it’s important that you understand these options in order to maximize the policy’s financial benefit and reduce potential taxes.
Here are six popular life-insurance settlement options:1. Lump sum: The beneficiary receives the full death benefit all at once in a single payment. 2. Interest Income: The insurance company retains the original death benefit and makes interest-only payments to the beneficiary. The original benefit may be paid in full to the beneficiary after a certain time period or to a contingent (alternate) beneficiary upon the primary beneficiary’s death.
3. Fixed Amount: The beneficiary is paid a fixed amount on a regular basis until the total death benefit (plus any interest accrued) has been paid out. If the beneficiary dies before all of the funds have been paid, a contingent beneficiary may receive the remaining amount.
4. Fixed Period: The beneficiary receives regular payments of both principal and interest over a fixed period of time, typically up to 30 years. If the beneficiary dies before the time period is over, the remaining balance may pass to a contingent beneficiary.
5. Life Income: The beneficiary receives guaranteed payments over the remainder of his or her life. The amount of the payments is determined by the insurance company and based on the beneficiary’s age and gender. The payments continue until the beneficiary dies. If he or she dies earlier than expected, the insurance company keeps the unpaid amount.
6. Life Income Period Certain: Unlike the life income option above, where payments stop when the beneficiary dies, this option guarantees fixed payments for a certain time period such as 10 or 20 years. If the beneficiary dies before the term expires, a contingent beneficiary may receive the remaining payments.
What about taxes?
Life insurance payouts made in a lump sum are not subject to income taxes. With other settlement options that pay out in installments over time, the original death benefit (principal) is not taxed, but any interest that accrues IS taxed as income when it is paid to the beneficiary.
Choosing a settlement
We can advise you on the settlement option that’s best suited for your particular needs. We can also support you in putting in place planning tools like trusts to protect the proceeds once they’re paid out. Schedule a Family Wealth Planning Session today to learn more.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Family Wealth Planning Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
Understanding Your Life Insurance Settlement Options
In the aftermath of rapper Nipsey Hussle’s murder this March, his family and ex-girlfriend have been locked in a bitter battle for custody of one of his young children. And as this ugly drama plays out in the courtroom and tabloids, it highlights the single-most costly estate-planning mistake a parent can make.Hussle, 34, whose given name was Ermias Ashgedom, was gunned down outside his South Los Angeles clothing store in March. His alleged killer, Eric Holder, was arrested and indicted for murder a few days later. The rapper’s death is particularly tragic, as his debut album, Victory Lap, was recently nominated for a Grammy Award.Yet even more tragic is what’s happening to Hussle’s kids. Because Hussle never named legal guardians, the decision of who will raise his two children—daughter Emani, 10, and son Kross, 2—is now up to the court. And this mistake is already having terrible consequences. In addition to not naming guardians for his kids, Hussle also failed to create a will, which makes their guardianship even more contentious. Hussle’s estate is estimated to be worth $2 million, and under California law, in the absence of a will, that money is to be split equally between his two kids. Given that both children are minors, however, they’re ineligible to access their inheritance until they reach the age of majority. This means that whomever ultimately wins guardianship of the children will likely gain control over their money as well.
Caught in the middle
Guardianship of Hussle’s son Kross, while still undecided, is currently not a source of conflict. Kross’s mother is actress Lauren London, who was Hussle’s longtime girlfriend, and Kross had been living with London at the time of his father’s death. She petitioned the court for her son’s guardianship, and there’s little doubt she’ll get it.
Who will be awarded guardianship of Hussle’s daughter Emani, however, is far less clear. Since the day of the shooting, Hussle’s sister, Samantha Smith, has been caring for Emani, who was living with her father when he was killed. Following Hussle’s shooting, Smith petitioned the court to obtain Emani’s guardianship. But Emani’s mother, Tanisha Foster, an old girlfriend of Hussle’s, is also seeking guardianship.Though Foster and Hussle shared custody of Emani, at the time of the rapper’s death, Hussle’s ex had reportedly not seen the child in months. Yet Foster claims that Emani was just visiting her dad on the day he was killed and that Smith and the rest of Hussle’s family are refusing to return her.Smith and Hussle’s family contend that Foster is unfit to raise the child due to her criminal past. Foster has a criminal record dating back to 2006, and she currently has a warrant out for her arrest after skipping a court hearing for a DUI charge. Yet Foster claims that her criminal history is irrelevant, and that as Emani’s mother, she’s the one who should be named as guardian. She’s also claiming that Smith unlawfully took custody of her daughter on the day of Hussle’s shooting.For now, the court is siding with Smith, ruling in May that Hussle’s sister can retain temporary custody of Emani, pending a final decision on her guardianship. That decision will likely be made in a court hearing scheduled for October.
Don’t leave your child’s life in a judge’s hands
As Hussle’s case so dramatically demonstrates, your death can strike at any time, so if you’re the parent of minor children, it’s imperative that you select and legally document long-term guardians for your kids. In fact, naming guardians for your children should be your number-one planning priority.
The fact that Hussle didn’t create a will is obviously another terrible mistake. But when it comes to your children’s lives, all the money in the world is meaningless in comparison. For this reason, we’re going to focus solely on the consequences resulting from Hussle’s failure to name legal guardians, and how easily the whole ugly mess could have been avoided.
As we’re seeing with Hussle, leaving it up to the court to name guardians for your kidscan lead to conflict, as otherwise well-meaning family members fight one another over custody. This process is not only costly, but it can be terribly traumatizing for everyone involved, especially your kids.Hussle’s case also shows how agonizingly slow this process often is. There have already been numerous court hearings related to Emani’s custody since her father’s death in March, and though the October hearing could finally decide her fate, it’s just as likely that the decision could be postponed again. Indeed, these custody battles often drag on for years, making the lawyers wealthy, while your kids are stuck in the middle.
But the most tragic consequence of Hussle’s failure to name legal guardians is that a judge will be the one who decides who’s best suited to care for his kids.Though we can’t be sure exactly who Hussle would have wanted to raise Emani, it’s almost certain he wouldn’t have wanted a total stranger to make that decision for him. Yet, because he didn’t take the time to document legal guardians, that’s exactly what’s going to happen.
Kids Protection Plan®
Helping you select and legally document long-term guardians for your children is one of our specialities. The founder of the Personal Family Lawyer® program, Alexis Katz, wrote a best-selling book on the subject titled Wear Clean Underwear!: A Fast, Fun, Friendly and Essential Guide to Legal Planning for Busy Parents. As a mother and one of the country’s leading estate-planning experts for families, Alexis was shocked to discover that the plan she created for her own daughter under the traditional planning model would have left her child at risk of being taken into the care of strangers, if anything happened to her and her husband. To address this gap in her plan, Alexis created a unique system known as the Kids Protection Plan®.
The system is a comprehensive methodology to guide you step-by step through the process of legally documenting guardians for your kids, for the short-term, long-term, and so much more. I’ve been trained to support you to put in place the Kids Protection Plan® for your minor children and/or children with special needs.
Getting started immediately
Because naming legal guardians for your kids is so critical, you can’t afford to wait to get the process started. If you have minor children—or children with long-term special needs—living at home, you should immediately use this resource, or contact us directly, to get started. And then schedule a follow-up visit with us to put a full Kids Protection Plan® in place. The numerous resources offered in the full plan go far beyond just naming long-term legal guardians.The Kids Protection Plan® also lets you grant the people you choose (along with backups) the legal authority to temporarily care for your children, until the long-term guardians can be located and formally named by the court. And you’re also able to confidentially, but in writing, exclude any person you know you’d never want to raise your kids.Indeed, the full Kids Protection Plan® offers a broad array of protective measures and materials designed to provide for the well-being, care, and love of your kids no matter what happens. Meet with us as your Personal Family Lawyer® today to ensure that your children and family never fall victim to the same tragic circumstances as Hussle’s.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Family Wealth Planning Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
A Lesson For All Parents: Who Will Be Emani’s Legal Guardian After the Death of Her Dad?
With societal attitudes about love, marriage, and parenting constantly evolving, our perception of what constitutes “family” is becoming more and more flexible. As family structures become more varied, we’re learning that when it comes to raising children, the marital status, gender, and even relationship status of the parents matters less and less.
What children need most are parents who are committed to loving and supporting them. Whether or not the parents have a romantic relationship with one another is immaterial to their ability to raise healthy and happy kids, so long as their co-parenting relationship is solid.
One new child-rearing trend that highlights this notion is platonic parenting. Also known as co-parenting, platonic parenting involves two or more people who agree to raise children together without a romantic connection. And we are discovering this nontraditional style of parenting can produce children who are just as well adjusted as those raised in a happily married household.
An alternative arrangement
Platonic parenting was pioneered within the LGBTQ community, where until recently same-gender couples couldn’t legally marry and didn’t have the court system to make up rules for them about post-breakup parenting. Following a romantic split, they were forced to create innovative, outside-the-box parenting arrangements on their own.
More recently, platonic parenting has spread to married couples looking to more effectively raise their children following divorce. By maintaining an amicable and cooperative relationship—sometimes even cohabitating—a couple whose romantic connection has dissolved can not only spare their children the trauma of divorce, but they may also find the arrangement is much healthier for them. Indeed, couples who stay unhappily married for the children’s sake often find the arrangement can be even more harmful to the whole family than a clean divorce.
And now, more and more people are choosing to raise children together using platonic parenting, without ever having a romantic relationship to begin with.
Parenting partnerships
Platonic parenting is particularly enticing for those who find themselves moving through their prime child-rearing years in the absence of a romantic relationship. For people who want to be parents, but aren’t interested in having a romantic partner, or simply haven’t found the right one yet, platonic parenting can be the ideal solution.
While raising a child on your own is perfectly acceptable, child rearing is an immense responsibility that lasts a lifetime. To help diffuse the tremendous demands parenting involves—and avoid the pressure to rush into romance—some individuals are turning to close friends in search of a co-parent.
And those who can’t find a suitable co-parent among their existing network of friends can use a number of websites dedicated to platonic parenting matchmaking. Websites like FamilyByDesign, CoParents.com, and Modamily enable prospective parents around the world to connect with one another to start a family.
Typically these arrangements involve conceiving through artificial insemination or in-vitro fertilization, and then raising the child in a platonic partnership. Some co-parents live separately and share custody, while others live together under the same roof like a traditional family.
There are even cases where the arrangement involves three or more platonic parents raising children together. Indeed, with today’s legal structures, people of all genders and sexual orientation are entering into a variety of platonic parenting relationships, putting a new spin on the notion of a blended family.
While platonic parenting might seem highly atypical and even controversial, given all of the work that goes into loving and raising children, it only makes sense that some would want to make parenting a team effort.
Planned parenthood
Just like any parenting arrangement, platonic parenting requires massive levels of trust, communication, and planning. The first step of the new partnership is for all parties to come up with a solid legal agreement governing the financial commitments and living situation.
Other issues to work out include how to handle new romantic relationships, if/how to incorporate platonic partners into family gatherings, along with all sorts of other basic ground rules. You’ll also need to talk about how to discuss the arrangement with any existing children and other family members, so everyone understands exactly what this new life will entail.
Create a legal foundation
With so many important agreements to be made, those seeking to create a platonic parenting arrangement should seek legal counsel at the outset of the relationship. We specialize in helping you navigate these types of non-traditional partnerships, and we offer a wide array of estate planning tools to help define the legal rights and responsibilities of each individual involved.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Family Wealth Planning Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
Is Platonic or Co-Parenting Right For You?
When you think about those loved ones who’ve passed away, you probably don’t think very much—or even at all—about the “things” they’ve left you. And when they do leave something behind, what you likely cherish most about the object are the memories and feelings it evokes, not the thing itself.
For the founder and CEO of New Law Business Model, Alexis Katz, the most treasured memento her late father left her wasn’t even something he intended to be special—it was just a random voicemail on her cellphone. And the message wasn’t meant to be anything sentimental.
His message simply said, “Lex, it’s your dad. Call me back.”
Following his death, Alexis loved listening to that message to hear her father’s voice. Of all the assets he left behind, that voicemail was what she cherished most.
Until one day, she went to listen to the message and discovered it had been erased—and her father’s voice was lost to her forever. She still recalls that day as one of her worst ever, yet like most painful events, it taught her an important lesson.
Losing that voicemail ultimately inspired Alexis to build a new feature into her family-centered model of estate planning, known as Family Wealth Legacy Passages. This feature, which is included in every plan we create, allows you to preserve and pass on something that’s inherently more valuable than any tangible asset you might leave your loved ones.
Preserving your intangible assets
We recognize that estate planning isn’t just about preserving and passing on your financial wealth and property when you die. When done right, planning allows you to share your family’s stories, values, and life lessons, so your legacy carries on long after you—and your money—are gone.
Family Wealth Legacy Passages is a process that’s designed to not only ensure these intangible assets never get lost, but also to make the process of documenting them as easy and convenient as possible. In this process, we guide you to create a customized recording in which you share your most insightful memories and life lessons, not just for your children and grandchildren, but for generations to come. My favorite part about this process is that most of our clients tell us that going through it helps them surface things they would have never thought about regarding how they want to parent differently or things they want to share now, during life, not just leave behind a lasting legacy of love.
To help inspire you, we’ve developed a series of helpful questions and prompts, which makes the process not only easy, but enjoyable. And this isn’t something you have to do on your own, which you’d probably never get around to doing, despite your best intentions. Instead, Family Wealth Legacy Passages is something we include as an integral part of our planning services—and it’s included at no extra charge with each plan we create.
In the end, your family’s most precious wealth is not money, but the memories you make, the values you instill, and the lessons you hand down. And left to chance, these assets are likely to be lost forever just like Alexis’s voicemail from her father.
Leave a lasting legacy
Our customized estate planning services will preserve and pass on not just your financial wealth, but your most treasured family values as well.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Family Wealth Planning Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
Use Estate Planning to Ensure Your Legacy Doesn’t Get Erased
In the first part of this series, we discussed how some professional adult guardians have used their powers to abuse the seniors placed under their care. Here, we’ll discuss how seniors can use estate planning to avoid the potential abuse and other negative consequences of court-ordered guardianship.
As our senior population continues to expand, an increasing number of elder abuse cases involving professional guardians have made headlines. The New Yorker exposed one of the most shocking accounts of elder abuse by professional guardians, which took place in Nevada and saw more than 150 seniors swindled out of their life savings by a corrupt Las Vegas guardianship agency.
The Las Vegas case and others like it have shed light on a disturbing new phenomenon—individuals who seek guardianship to take control of the lives of vulnerable seniors and use their money and other assets for personal gain. Perhaps the most frightening aspect of such abuse is that many seniors who fall prey to these unscrupulous guardians have loving and caring family members who are unable to protect them.
In the first part of this series, we detailed how criminally minded individuals can take advantage of an overloaded court system and seize total control of seniors’ lives and financial assets by gaining court-ordered guardianship. Here we’ll discuss how seniors and their adult children can use proactive estate planning to prevent this from happening.
It’s important to note that any adult could face court-ordered guardianship if they become incapacitated by illness or injury, so it’s critical that every person over age 18—not just seniors—put these planning vehicles in place to prepare for a potential incapacity.
Keep your family out of court and out of conflict
Outside of the potential for abuse by professional guardians, if you become incapacitated and your family is forced into court seeking guardianship, your family is likely to endure a costly, drawn out, and emotionally taxing ordeal. Not only will the legal fees and court costs drain your estate and possibly delay your medical treatment, but if your loved ones disagree over who’s best suited to serve as your guardian, it could cause bitter conflict that could unnecessarily tear your family apart.
Furthermore, if your loved ones disagree over who should be your guardian, the court could decide that naming one of your relatives would be too disruptive to your family’s relationships and appoint a professional guardian instead—and as we’ve seen, this could open the door to potential abuse.
Planning for incapacity
The potential turmoil and expense, or even risk of abuse, from a court-ordered guardianship can be easily avoided through proactive estate planning. Upon your incapacity, an effective plan would give the individual, or individuals, of your choice immediate authority to make your medical, financial, and legal decisions, without the need for court intervention. What’s more, the plan can provide clear guidance about your wishes, so there’s no mistake about how these crucial decisions should be made during your incapacity.
There are a variety of planning tools available to grant this decision-making authority, but a will is not one of them. A will only goes into effect upon your death, and even then, it simply governs how your assets should be divided. To this end, a will does nothing to keep your family out of court and out of conflict in the event of your incapacity—nor does it help you avoid the potential for abuse by professional guardians.
Your incapacity plan shouldn’t be just a single document. It should include a variety of planning tools, including some, or all, of the following:
- Healthcare power of attorney: An advanced directive that grants an individual of your choice the immediate legal authority to make decisions about your medical treatment in the event of your incapacity.
- Living will: An advanced directive that provides specific guidance about how your medical decisions should be made during your incapacity.
- Durable financial power of attorney: A planning document that grants an individual of your choice the immediate authority to make decisions related to the management of your financial and legal interests.
- Revocable living trust: A planning document that immediately transfers control of all assets held by the trust to a person of your choosing to be used for your benefit in the event of your incapacity. The trust can include legally binding instructions for how your care should be managed and even spell out specific conditions that must be met for you to be deemed incapacitated.
- Family/friends meeting: Even more important than all of the documents we’ve listed here, the very best protection for you and the people you love is to ensure everyone is on the same page. As part of our planning process, we’ll walk the people impacted by your plan through a meeting that explains to them the plans you’ve made, why you’ve made them, and what to do when something happens to you. With a team of people who love you, watching out for you and what matters most, the risk of abuse from a professional guardian is low.
It could be a good idea (though it’s not mandatory) to name different people for each of the roles in your planning documents. In this way, not only will you spread out the responsibility among multiple individuals, but you’ll ensure you have more than just one person invested in your care and supervision. In that case, it’s even more critical that everyone you’ve named understands the choices you’ve made, and why you have made them.
Don’t wait to put your plan in place
It’s vital to understand that these planning documents must be created well before you become incapacitated. You must be able to clearly express your wishes and consent in order for these planning strategies to be valid, as even slight levels of dementia or confusion could get them thrown out of court.
Not to mention, an unforeseen illness or injury could strike at any time, at any age, so don’t wait—contact us right away to get your incapacity plan taken care of.
Finally, it’s crucial that you regularly review and update these planning tools to keep pace with life changes, including changes in your assets or the nature of your relationships. If any of the individuals you’ve named becomes unable or unwilling to serve for whatever reason, you’ll need to revise your plan. We can help with that, too.
Retain control even if you lose control
To avoid the total loss of autonomy, family conflict, and potential for abuse that comes with a court-ordered adult guardianship, you can use estate planning to ensure that you at least have some control over your how your life and assets will be managed if it ever does occur.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Family Wealth Planning Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.

Use Estate Planning to Avoid Adult Guardianship—and Elder Abuse: Part 2
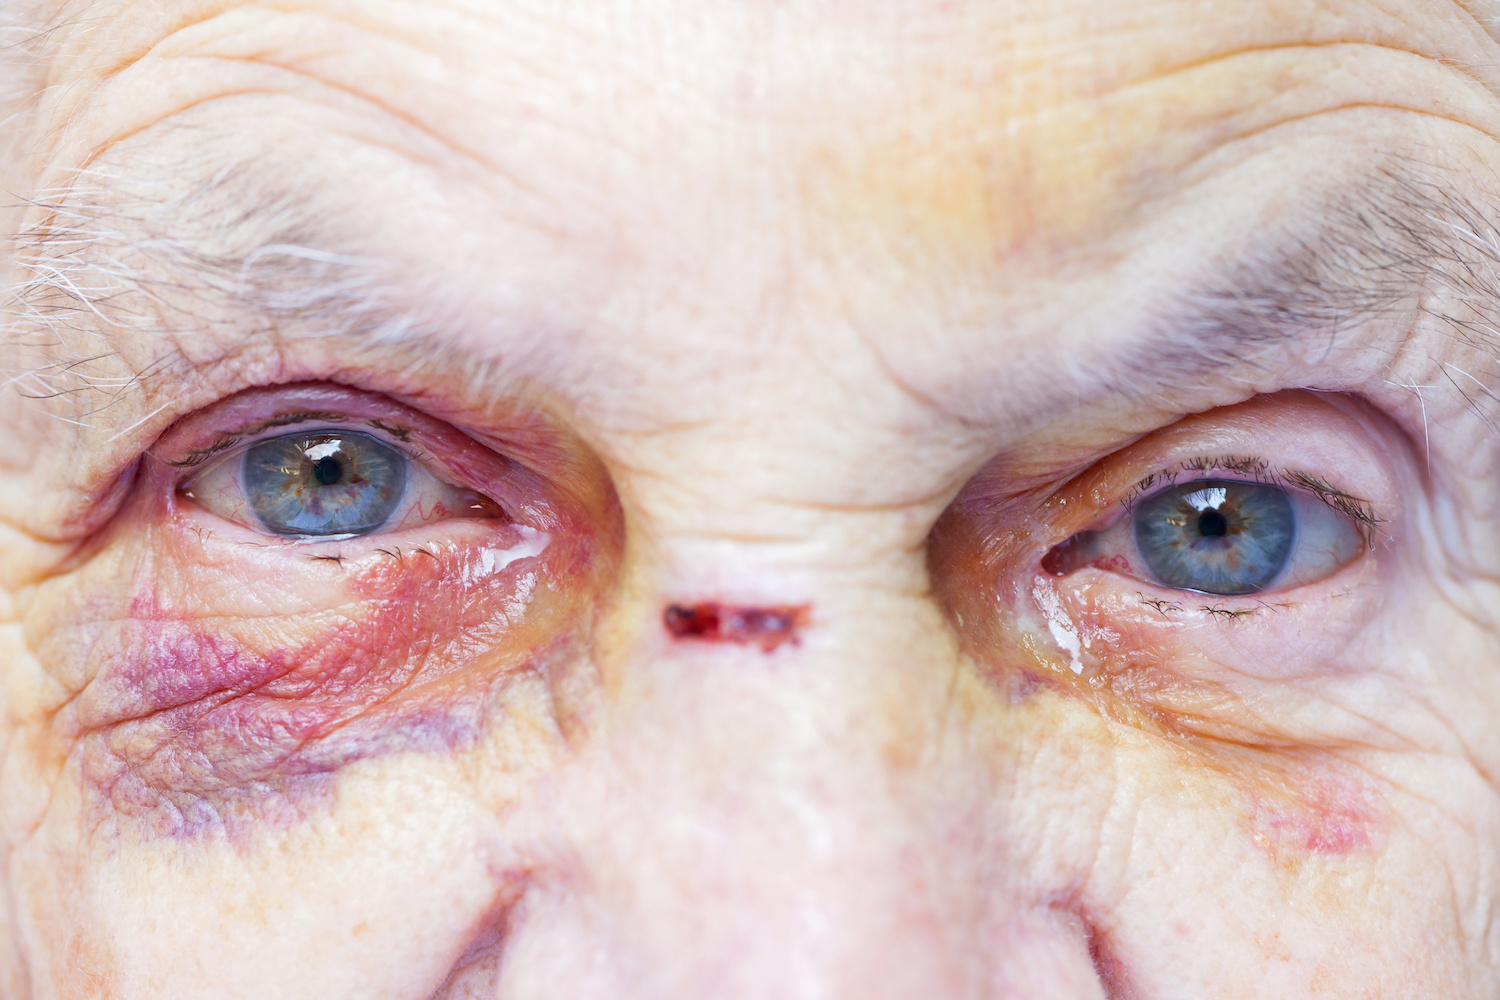
Elder abuse can take a wide variety of forms, but we think the worst of the worst is caused by unscrupulous adult guardians appointed by a court to care for seniors who are no longer able to care for themselves. And though you may not want to believe such a thing could happen, you need to know that without the right planning in place, even the seniors in your own family could be at risk. In fact, there are currently 1.5 million American adults under guardianship, with an estimated 85% of them over age 65. All total, these guardians control nearly $273 billion in assets. And a 2010 report by the Government Accountability Office (GAO) found hundreds of cases where guardians were involved in the abuse, exploitation, and neglect of seniors placed under their supervision.
Exploitation disguised as protection
Although most of the reported abuse was committed by family members, an increasing number of elder abuse cases involving professional guardians have recently made the headlines. The New Yorker exposed one of the most shocking accounts of elder abuse by professional guardians, and the abuse suffered by these victims is so horrendous, it’s hard to believe.
The case involved the owner of a Las Vegas guardianship agency, who was indicted on more than 200 felonies for using her guardianship status to swindle more than 150 seniors out of their life savings. The craziest part of this is that many of those seniors had loving and caring family members, who were unable to protect their senior family members.
That case and similar cases of criminal abuse by professional guardians across the country has shed light on a disturbing new phenomenon—individuals who seek guardianship to take control of the lives of vulnerable seniors and use their money and other assets for personal gain. These predatory guardians search for seniors with a history of health issues, and they’re often able to obtain court-sanctioned guardianship with alarming ease. From there, they can force the elderly out of their homes and into assisted-living facilities and nursing homes. They can sell off their homes and other assets, keeping the proceeds for themselves. They can prevent them from seeing or speaking with their family members, leaving them isolated and even more vulnerable to exploitation.
What’s more, though it’s possible for a guardianship to be terminated by the court if it can be proven that the need for guardianship no longer exists, a study by the American Bar Association (ABA) found that such attempts typically fail. And those family members who do try to fight against court-appointed guardians frequently end up paying hefty sums of money in attorney’s fees and court costs, with some even going bankrupt in the process.
An open door for potential abuse
Obviously, not all professional guardians exploit the seniors (known as wards) placed under their care. But with the combination of the exploding elderly population—many of whom will require guardians—and our overloaded court system, such abuse will almost certainly become more common. Indeed, as the swelling aging population strains court resources, strict oversight of professional guardians is likely to become increasingly more difficult, enabling shady guardians to more easily slip through the cracks.Facing these facts, it’s critical for both seniors and their adult children to take proactive measures to prevent the possibility of such abuse. Fortunately, there are multiple estate planning tools that can dramatically reduce the chances of you or your elderly loved ones being placed under the care of a professional guardian against your/their wishes.
What’s more, because any adult could face court-ordered guardianship if they become incapacitated by illness or injury, it’s crucial that every person over age 18—not just seniors—have planning vehicles in place to prepare for their potential incapacity.
Should you become incapacitated and not have the proper planning vehicles in place, your family would have to petition the court in order to be granted guardianship. And it’s this lack of planning that leaves you vulnerable. In most cases, the court would appoint a family member as guardian, but this isn’t always the case. If you have no living family members, or those you do have are unwilling or unable to serve or deemed unsuitable by the court, a professional guardian would be appointed. And in certain cases, particularly when your family doesn’t live close by, guardianship can be granted without your loved ones—or even you—being aware of it.
In the Las Vegas abuse case, for example, unscrupulous professional guardians were able to file emergency “ex-parte” (in secret) petitions seeking guardianship of vulnerable seniors they sought to exploit. The ex-parte status meant that neither the seniors, nor their family members were notified of the guardianship hearing. Behind closed doors, the nefarious guardians convinced a judge that immediate guardianship was necessary to prevent their elderly victims from harming themselves.
When family members realized what had happened and tried to contest the guardianship and seek guardianship themselves, they were disparaged in court as being neglectful and only interested in their elderly relatives’ money. This led the court to deem those family members unsuitable, leaving the professional guardianship in place indefinitely.
A total loss of autonomy
Once you’ve been placed under court-ordered guardianship, you essentially lose all of your civil rights. Indeed, whether it’s a family member or a professional, guardians have complete legal authority to control every facet of your life. A few of the primary powers guardians have include the following:
- Determining where you live, including moving you into a nursing home
- Complete control over your finances, real estate, and other assets
- Making all of your healthcare decisions and providing consent for medical treatments
- Placing restrictions on your communications and interactions with others, including family members
- Making decisions about your daily life such as recreational activities, clothing, and food choices
- Making end-of-life and other palliative-care decisions
Given the extreme power guardianship affords, courts are supposed to exercise tight oversight over adult guardians, yet most states provide only cursory supervision. What’s more, states often don’t even keep complete records of guardianship cases, and those states that do keep records typically keep the records sealed from public view.Indeed, the 2010 GAO report noted, “We could not locate a single Website, federal agency, state or local entity, or any other organization that compiles comprehensive information on this issue.” With no government agency tasked with preventing abuse by professional guardians, it’s up to you to protect yourself through proactive estate planning.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Family Wealth Planning Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.