Welcome to the Blog
Keep up with the latest news and updates
Is California’s New Transfer on Death Deed a Safe Alternative to a Living Trust?
Perhaps you’ve heard from a well-meaning friend or advisor that you can use an inexpensive Transfer on Death Deed to keep your property out of court without going to the trouble of creating a Living Trust. If so, read this before you rely on a Transfer on Death Deed to ensure that you aren’t creating more trouble for the people you love.
On January 1, 2016, Assembly Bill 139 went into effect, providing California residents with a new way to transfer residential property to their heirs. Specifically, the law creates a Revocable Transfer on Death Deed (TOD Deed), intended to be a simple tool for transferring ownership of real property to beneficiaries upon the property owner’s death.
The law was initially heralded as a welcome alternative to Revocable Living Trusts, which some believe to be costly, time consuming, and complex. A TOD Deed allows named beneficiaries to assume ownership of your residential property without undergoing probate or trust administration.
However, before you rely on a TOD Deed as a cheaper alternative to full-on Revocable Living Trust planning, consider these factors …
First, the TOD Deed only applies to certain types of real property:
- A single-family home or condominium,
- A single-family residence on agricultural property of 40 acres or less, or
- A multi-family residence with no more than four units.
Moreover, a TOD Deed has several other restrictions and requirements.
- It must be signed and dated before a notary to be valid.
- It must be recorded within 60 days from the date it’s signed.
- It does not permit designation of beneficiaries by class (e.g. “my siblings”).
- It must strictly adhere to the form prescribed by the statute.
Finally, and most importantly BEWARE of these major risks: The TOD Deed offers no protection from your creditors.
- If your property is held joint tenancy, your joint tenant becomes the sole owner upon your death and has full control of the property, and your Transfer on Death Deed is inapplicable.
- Unlike with a Living Trust, a Transfer on Death Deed cannot be used to manage, sell, or borrow against the property during your incapacity. This means that if you become incapacitated, there’s no action your beneficiary can take to get access to using your property as a resource for your care, as your Trustee could, if you had your property in a Revocable Living Trust.
- If the beneficiary is a minor upon your death, a court-appointed custodian will need to be named to control your property until the child reaches legal age. With a Living Trust, you get to name the person to handle the property until your child reaches legal age, and you can even set up your trust so that when your child does inherit it, he or she can receive it protected from a future divorce or future creditors.
- Title insurance companies have been reluctant to insure clear title until three years after the grantor’s death when a Transfer on Death deed is used. During this time, the beneficiary will likely be unable to sell or borrow against the property.
- The property may be subject to Medi-Cal Estate Recovery, if you received Medi-Cal benefits.
Unless extended, the new law will sunset on January 1, 2021, but TOD Deeds executed before that date will remain valid.
Warning: Since its inception, significant flaws have been found within the statute, and some advocates believe it will lead to increased elder abuse. For more on this, read a letter from the Executive Committee of the Trusts & Estates Section of the California Bar, appended as an exhibit to the California Law Revision Commission’s Memorandum # 2017-35.
Given these concerns, we recommend against the use of the TOD Deed and advise those seeking to transfer their real estate in a manner that is best for you, and the people you love to schedule a Estate Plan Strategy Session with us to choose an option that will best meet your needs.
Is California’s New Transfer on Death Deed a Safe Alternative to a Living Trust?
Could an Out of Date Will Leave You Facing Eviction?
It’s all too common, but unfortunately the way some lawyers handle their clients’ estate plans create more problems than solutions for future generations.
It’s critical that you understand exactly what will happen after you become incapacitated or when you die, to ensure that the people you love don’t end up cleaning up an estate planning nightmare while also grieving your passing.
Recently in Columbus, Ohio, a mom of four kids is not only grieving the death of her mother, but now also facing eviction from her home.
Here’s how it happened: Grandma signed a will in mid-2015 putting all of her assets in trust for the education of her six grandchildren. She indicated that her local bank should manage those assets for the benefit of the education of those grandchildren. That seems like a great thing to do, right?
Right. Except that then in 2016, Grandma then bought a home for one of her daughters and her daughter’s four children. And she didn’t update her will. Unfortunately, this oversight is far too common due to the way many lawyers serve their clients. Their estate plans are often just focused on the documents and the one-time transaction, rather than ensuring they work with their clients on an ongoing basis, updating those documents each time life changes or asset changes occur.
So now, the daughter that is living in the house with her four children is being evicted. The bank was tasked with providing for the education of the children, so the bank is now selling the house with the intention of putting the money in trust for their education. Then, when they turn 21, they will get a distribution of whatever is left.
It’s hard to imagine that Grandma would have wanted this outcome for her daughter and four of her grandchildren. But without a clear plan that documents Grandma’s wishes, which could have included her daughter paying rent to the trust account for the benefit of all the grandchildren, the bank is within its right to evict the daughter and the four grandkids.
It’s a sad, sad tale. And one that could have been easily avoided if Grandma’s lawyer had foreseen the potential issues and supported grandma to update her will.
When is the last time you had your estate plan reviewed? Have you developed a relationship with a trusted lawyer who you feel confident has your back and will make sure that your kids aren’t facing eviction or some other unexpected mess after your incapacity or death? If not, now is the time.
Could an Out of Date Will Leave You Facing Eviction?
Life insurance is a purchase only made once or twice in a lifetime, so it is common to be unaware of the ins and outs of policy protection. The potential pitfalls are significant, however, so review the following tips and learn how to buy life insurance like a pro.
Get the Right Type of Amounts
Life insurance policies are generally sold by highly commissioned sales people or by order takers. In either case, you need to be sure you are in the know, before you buy, lest you get sold a policy or amount you don’t need, or you overlook the types and amounts that are right for you. We can help you make objective decisions about your insurance needs, with no commissions payable to us, so you know you’re getting our 100% on your side analysis.
Don’t Name a Minor as a Beneficiary
If you’ve named a minor child as a beneficiary, or even a secondary beneficiary, after your spouse, you could be creating double trouble. First, your life insurance would have to go through a court process and subject to the control of a financial guardian, and then second, whatever is left would be distributed to your minor child when he or she turns 18. You can easily avoid this by naming a trust as beneficiary of your life insurance, thereby keeping your life insurance out of court and ensuring your child doesn’t receive control until he or she is ready. Plus, then you get to decide who takes care of the life insurance money you are leaving behind, until it’s distributed to your child. And, you can even build in protection against your child’s future divorce, or any creditor issues.
Term Insurance to Fund Divorce Settlements
If you receive child support and alimony, insist that your spouse have a term life insurance policy to guarantee you are able to collect on your settlement, even if your ex-spouse dies while still paying out your divorce settlement.
Compare Quotes for Whole and Term
Experts suggest most people only need life insurance to cover their working years and while they raise a family. Term life insurance is typically affordable and covers you when you need it most. Permanent insurance is best when you know you will have estate taxes to cover OR if you want to use insurance as an investment vehicle with guaranteed returns, but often big commissions to make up in the early years of the policy. One of the services we provide to our member clients is to review all insurance policies, both in place and those being considered, to provide objective evaluation before you buy.
Don’t Overlook Living Benefits
A living benefits rider could allow you to access funds if you were diagnosed as terminally ill or with a chronic and debilitating condition.
If you are ready to purchase a life insurance policy that works for you, start by sitting down with a Personal Family Lawyer®. As your Personal Family Lawyer®, we can walk you step by step through creating a financial plan that will help you provide for your family no matter what. A Personal Family Lawyer® offers Estate Plan Strategy Sessions that help you protect and preserve your wealth for future generations. Before the session, we’ll send you a Family Wealth Inventory and Assessment to complete that will get you thinking about what you own, what matters most to you, and what your wishes are when you die. Schedule online.
How to Buy Life Insurance Like a Pro
Planning to Protect Your Assets
Asset protection planning is an important step to take in safeguarding your hard-earned assets from being lost, inadvertently, because you overlooked something important.
The most foundational level of asset protection is to plan for what will happen to your assets in the event of your incapacity or death because you are 100% guaranteed to have one or both of those happen to you.
If you become incapacitated or die without proper planning in place, your assets will get stuck in the court system, and could be delayed in getting to your loved ones’ or even lost. If you have not reviewed your planning for death or incapacity in the past couple of years (or ever at all), you will want to call us for a Estate Plan Strategy Session as soon as possible.
And, what about planning to protect assets from things that could happen during life, such as potential litigation, taking on too many debts, accidents or other mishaps?
First and foremost, buy insurance! Insurance can do two things an asset protection plan can’t: pay to defend you in the event a lawsuit is brought against you and pay to settle any lawsuits. Bottom line: insurance says I love you. And, if you need it, you’ll be glad you have it.
As part of your Estate Plan Strategy Session, we will look at the types and amounts of insurance you have, and determine what else may be needed, or if you are even over-insured.
If you have a business, make sure you’ve fully separated personal and business assets. And that you are using your business entity properly, to ensure that any business activities are kept within your business entity, and that you have us review any personal guarantees before you sign something that could create personal liability for you.
If you need more thorough asset protection, due to an upcoming marriage, or engaging in other risky behavior, please contact us sooner rather than later.
Asset protection cannot happen after something happens. It must be set up ahead of time to be effective, and so it must happen now, if you want to get set up right.
Protecting your assets takes know-how. If you’re ready to develop a smart asset protection plan, consider sitting down with a Personal Family Lawyer®. As your Personal Family Lawyer®, we can help you with your asset protection planning needs. Our Estate Plan Strategy Session guides you to protect and preserve what matters most. Before the session, we’ll send you a Family Wealth Inventory and Assessment to complete that will get you thinking about what you own, what’s most important to you, and what you can do to ensure your family is taken care of.

Planning to Protect Your Assets
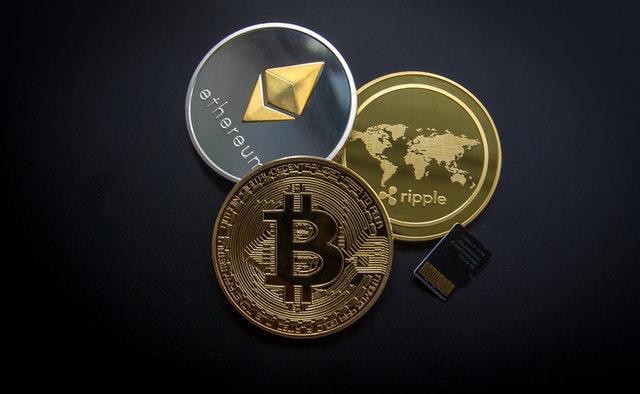
Unless you’ve been living under a rock, you’ve probably heard about Bitcoin. But, you may not know what it is or how it affects your estate planning. Or, maybe you’ve got yourself some Bitcoin, but haven’t given thought to what would happen to your digital currency in the event of your death or incapacity. So, today’s article will dive in with some initial thoughts of what happens to cryptocurrency when you die, and then we’ll get deeper in future articles.
There are now over 800 digital currencies available, though Bitcoin is the most well known.
And each one operates a bit differently, and with a different purpose.
What they all have in common is that they are digital currencies, in the form of “tokens” that you can now buy (or invest in) and in some cases use to exchange for goods and services.For example, more and more providers of goods and services are accepting Bitcoin as a payment method, just as they would cash or credit.
And, even a few accepting the lesser known currency called Ripple (XRP).
But, as of this writing, there are no providers we’ve heard of accepting, for example, the lesser known cryptocurrency of ProCoin (PROC), a coin based on shopping rewards. But, the coin is tradable on the open coin market, currently at $.12, though it’s been traded as high as $.38.
If you want to learn more about how these digital currencies work, please do let me know and I’ll write more about it in the future.
For today, I want to cover what you need to make sure you’ve got in place from a “what happens when you become incapacitated or die” perspective if you are holding digital currency.
Because if you have not planned for the transfer of your digital currency at the time of your incapacity or death, it could literally be lost to the ethers. And, if you invested in Bitcoin back in the day before it got popular, that could potentially be millions of dollars lost to your loved ones.
There are two things for you to consider if you are holding digital currency
- That your loved one’s (or whoever you would want to have your currency) know about it; and
- That they know how to access it and cash it in or hold onto it.
If you are holding your currency in an exchange, such as coinbase, with 2-factor authentication, it could be very difficult for your loved one’s to access your currency. We are in process of setting up a digital account administration system for our clients and you can look forward to that in the coming months. Having that in place would allow the executor of your estate to handle all digital accounts, not just crypto accounts.
Until then, best practice is to transfer your cryptocurrency into a “paper wallet”, which is kind of ironic given that it’s a digital currency. And it basically involves storing codes offline that allow you to access your currency. Here’s the thing, if you lose those codes, or your loved ones can’t find them, it’s the same as all of your currency being gone.
You can read more about the different storage options for cryptocurrency here.
Bottom line: if you have cryptocurrency and you want your loved ones to have it after you are gone, you should probably call us so we can make sure it’s not lost upon your incapacity or death.
As a new technology, cryptocurrency can be a bit confusing, and not many lawyers are even thinking about this issue yet. But we are, so give us a call and let’s have a Estate Plan Strategy Session during which we can help you to protect and preserve what matters most. Before the session, we’ll send you a Family Wealth Inventory and Assessment to complete that will get you thinking about what you own, what’s most important to you, and what you can do to ensure your family is taken care of. Schedule online.
Bitcoin, Ethereum, and the Blockchain — What Happens When You Die?
Dealing with the financial stressors of caring for an aging loved one can affect your ability to provide them with the care and compassion they need. It can also put the security of your financial future at risk. To mitigate these concerns, consider these useful tips to help you make informed decisions about how to protect your retirement while caring for senior parents.
Don’t Leave Your Job
Many adult children end up putting their professional lives on hold to become a primary caregiver for their elderly parents. Financial experts advise against this because of the sudden loss of income and valuable benefits. Consider caregiving options that support your ability to maintain your earning potential.
Create a Budget
Review the actual costs of being a primary caregiver before making any drastic changes like leaving your job. Also, consider whether your loved one’s assets can be utilized to cover some of the costs involved in providing care inside or outside the home.
Look for Benefits Elsewhere
Free or low-cost benefits that can help cover some of the costs of caregiving, such as home health aides, are often available to seniors. Similarly, review the limitations of public benefit options such as Medicare and Medicaid.
Consider Relocating Your Parent
It is common for seniors to prioritize remaining in their own home while they age. Although understandable, this can be a very expensive, and often unrealistic option. If opening your home to your loved one is an option, it can be far less expensive.
Seek Professional Help
Geriatric care managers can help you establish a caregiving plan that meets your needs and assist you in identifying resources to save time and money.
Protect Your Parent From Scams
Financial elder abuse is on the rise, so make sure your loved one’s finances are protected. Telephone, postal mail, and internet fraud is common and can be easily avoided when a close relative or friend is keeping tabs on the accounts of a senior loved one. Consider talking with your parents about stepping down as Trustee of their trusts and letting you step in now to monitor their finances, and if they do not have a Trust holding title to their accounts, meet with us now to look at whether it makes sense to set that up for them (and for you).
Discuss the Future
Now is an opportune time to review your loved one’s wishes for his or her estate and consider your own financial goals and how helping to care for a loved one might affect them.
Caring for a loved one can take a toll, both financially and emotionally. If you are ready to create a financial plan for caregiving, start by sitting down with a Personal Family Lawyer®. A Personal Family Lawyer® can help you plan for changes in life at every stage. Our Estate Plan Strategy Session guides you to protect and preserve what matters most. Before the session, we’ll send you a Family Wealth Inventory and Assessment to complete that will get you thinking about what you own, what’s most important to you, and what you can do to ensure your family is taken care of. Schedule online.

How To Protect You Retirement While Caring For Senior Parents
In the sea of financial planning wisdom, there are too few messages about the importance of mindset. Think your salary can bring you safely to retirement? Think again. Gone are the days when simply saving money was enough to get you to retirement. With pensions practically a thing of the past, it takes more than just a big piggy bank to afford retirement. Do you need a second income to afford retirement?
Saving strategies aside, changing your mindset from that of a consumer to thinking like an investor, or even an entrepreneur through a side hustle, can give you the security you’ll need to ensure a comfortable retirement.
Many people believe that investing wisely is the key to taking your retirement planning into the 21st century, but is it really enough? Smart financial advisors recommend multiple income streams to ensure you can retire comfortably. Even with a healthy retirement savings, it is wise to look for ways to diversify your income sources.
Enter: the side hustle. Your side hustle (i.e. a second job, side business, or income-generating investment) boosts your income while minimizing risk that you’ll run out of money down the road. Your salary isn’t guaranteed, but with a side hustle (or a few), you won’t put your retirement in jeopardy if you lose your job or change jobs.
If an advisor focuses just on the certain amount you need to save by age 55 to retire, they might not have your best interests in mind. In reality, there is no magic number. No one can predict how much you’ll need or even tell you where you need to keep your money. That’s why it’s so important not to limit your retirement planning to simple money saving techniques.
If you are ready to take the next step toward planning wisely for your retirement on the road to reaching financial independence, start by sitting down with us. As your Personal Family Lawyer®, we will walk you step by step through creating a plan that will help you achieve your financial goals. Ask about your Money Map Planning Process or start with a Estate Plan Strategy Session, which will give you absolute clarity on what you own, and what will happen to all of it when something happens to you, so you can make informed, empowered decisions for the one’s you love. Before the session, we’ll send you a Family Wealth Inventory and Assessment to complete that will get you thinking about what you own, what matters most to you, and about your wishes in case you become incapacitated or when you die. Schedule online.

Think Your Salary Can Bring You Safely to Retirement? Think Again.
Trusts vary in their structure, funding, and terms, so it’s hard to know how divorce will impact your trust without review. It’s safe to say, without question, your trust (and really your entire estate plan) should be reviewed during your divorce to prevent unforeseen negative outcomes.
The impact of a divorce on your trust can depend on:
The Trust’s Structure
Trusts frequently name the spouse as a trustee and beneficiary. In divorce, clarify your wishes in regards to these provisions. Even if you want to keep each other in your financial plans going forward, the trust should be amended appropriately after your divorce is complete, so your intention is clear.
Whether It’s Revocable or Irrevocable
If it’s revocable, changing the terms of the trust is easy, but you may have to wait until after your divorce is final to do it due to “orders” that go into effect when you file for divorce that prevent you from moving assets. If your trust is irrevocable, it might be necessary to petition the court to change the trustees, and the trust assets themselves may or may not be part of the divorce judgment.
Your State’s Laws on Community Property
Divorcing parties sometimes attempt to shield assets in trusts to keep them out of the pockets of the soon to be ex. When done surreptitiously, this could significantly complicate the divorce. Even when the assets in a trust are separate property, the income from the trust might still be considered for child support and alimony purposes.
Trusts can be affected by divorce, so you should take steps to protect your trust and your intentions. If you are ready to take that step, meet with us for guidance.
As your Personal Family Lawyer®, we can help you navigate your divorce so your assets, including those held in trusts, remain under your direction and control. Our Estate Plan Strategy Session guides you to protect and preserve what matters most. Before the session, we’ll send you a Family Wealth Inventory and Assessment to complete that will get you thinking about what you own, what’s most important to you, and what you can do to ensure your family is taken care of.
Divorcing? Here’s What You Should Know About How it May Affect Your Trust
A celebrity’s image and likeness can continue to produce considerable income after death. This type of intellectual property is considered part of your estate, and the IRS can tax its value. In the case of pop star Michael Jackson’s estate, that recently meant an IRS bill to the tune of $64.5 million, years after his death, which is about 40% of his likeness’ valuation of $161 million. We can all learn tax lessons from celebrity estate plans.
Michael Jackson’s estate planning fail could certainly have been avoided by using one of these estate-planning strategies that minimize the taxable value of a person’s image and likeness.
Charitable Bequests
Robin Williams made a charitable bequest of his image and likeness to a foundation. It was set up in his name, allowing his estate to get a charitable deduction against the estate tax.
Time Bans
Williams also established a 25-year time ban to prevent any future exploitation of his image. A time restriction lowers the value of a celebrity’s name and likeness because the value is typically lower at the end of the ban than at the date of death.
State of Residence
Some states don’t recognize inheritable postmortem rights to likeness. This means the estate can’t profit from it. Consider your state’s laws when estate planning so you can benefit from any available tax breaks.
Consult with Multiple Appraisers
Get one appraisal and have another appraiser act as a consultant to point out where there might be room to argue against the valuation.
Celebrity estate planning fails grace the cover of tabloids and news sites as soon as weeks after their deaths. Fortunately, they provide valuable estate planning lessons for the rest of us. While their fails may be more expensive, even a small fail can have a huge impact on your family’s future and well-being. Don’t leave your family holding the bag, especially an empty one.
Your family is worth the time for you to have a Family Wealth Planning Session with us so you can make empowered, informed choices for the people you love. As your Personal Family Lawyer®, we can walk you step by step through a process that will minimize your tax liability and keep your family out of court and out of conflict.
Our Family Wealth Planning Session guides you to protect and preserve what matters most. Before the session, we’ll send you a Family Wealth Inventory and Assessment to complete that will get you thinking about what you own, what’s most important to you, and what you can do to ensure your family is taken care of and you’ll leave the Session with absolute clarity about how to make the best choices for your life and death. Schedule online.