Welcome to the Blog
Keep up with the latest news and updates
When it comes to estate planning, most people automatically think about taking legal steps to ensure the right people inherit their stuff when they die. And these people aren’t wrong.
Indeed, putting strategies in place to protect and pass on your wealth and other assets is a fundamental part of the planning equation. However, providing for the proper distribution of your assets upon your death is just one part of the process. And it’s not even the most critical part. Planning that’s focused solely on who gets what when you die is ignoring the fact that death isn’t the only thing you must prepare for. You must also consider that at some point before your eventual death, you could be incapacitated by accident or illness.Like death, each of us is at constant risk of experiencing a devastating accident or disease that renders us incapable of caring for ourselves or our loved ones. But unlike death, which is by definition a final outcome, incapacity comes with an uncertain outcome and timeframe.
Incapacity can be a temporary event from which you eventually recover, or it can be the start of a long and costly event that ultimately ends in your death. Indeed, incapacity can drag out over many years, leaving you and your family in an agonizing limbo. This uncertainty is what makes incapacity planning so incredibly important.
In fact, incapacity can be a far greater burden for your loved ones than your death. This is true not only in terms of its potentially ruinous financial costs, but also for the emotional trauma, contentious court battles, and internal conflict your family may endure if you fail to address it in your plan. The goal of effective estate planning is to keep your family out of court and out of conflict no matter what happens to you. So if you only plan for your death, you’re leaving your family—and yourself—extremely vulnerable to potentially tragic consequences.
Where to start
Planning for incapacity requires a different mindset and different tools than planning for death. If you’re incapacitated by illness or injury, you’ll still be alive when these planning strategies take effect. What’s more, the legal authority you grant others to manage your incapacity is only viable while you remain alive and unable to make decisions about your own welfare. If you regain the cognitive ability to make your own decisions, for instance, the legal power you granted others is revoked. The same goes if you should eventually succumb to your condition—your death renders these powers null and void.To this end, the first thing you should ask yourself is, “If I’m ever incapacitated and unable to care for myself, who would I want making decisions on my behalf?” Specifically, you’ll be selecting the person, or persons, you want making your healthcare, financial, and legal decisions for you until you either recover or pass away.
You must name someone
The most important thing to remember is that you must choose someone. If you don’t legally name someone to make these decisions during your incapacity, the court will choose someone for you. And this is where things can get extremely difficult for your loved ones.
Although laws differ by state, in the absence of proper estate planning, the court will typically appoint a guardian or conservator to make these decisions on your behalf. This person could be a family member you’d never want managing your affairs, or a professional guardian who charges exorbitant fees. Either way, the choice is out of your hands.Furthermore, like most court proceedings, the process of naming a guardian is often quite time consuming, costly, and emotionally draining for your family. If you’re lying unconscious in a hospital bed, the last thing you’d want is to waste time or impose additional hardship on your loved ones. And this is assuming your family members agree about what’s in your best interest.
For example, if your family members disagree about the course of your medical treatment, this could lead to ugly court battles between your loved ones. Such conflicts can tear your family apart and drain your estate’s finances. And in the end, the individual the court eventually appoints may choose treatment options, such as invasive surgeries, that are the exact opposite of what you’d actually want.
This potential turmoil and expense can be easily avoided through proper estate planning. An effective plan would give the individuals you’ve chosen immediate authority to make your medical, financial, and legal decisions, without the need for court intervention. What’s more, the plan can provide clear guidance about your wishes, so there’s no mistake or conflict about how these vital decisions should be made.
What won’t work
Determining which planning tools you should use to grant and guide this decision-making authority depends entirely on your personal circumstances. There are several options available, but choosing what’s best is something you should ultimately decide after consulting with an experienced lawyer like us.
That said, we can tell you one planning tool that’s totally worthless when it comes to your incapacity: a will. A will only goes into effect upon your death, and then it merely governs how your assets should be divided, so having a will does nothing to keep your family out of court and out of conflict in the event of your incapacity.
The proper tools for the job
There are multiple planning vehicles to choose from when creating an incapacity plan. And this shouldn’t be just a single document; instead, it should include a comprehensive variety of multiple planning tools, each serving a different purpose.
Though the planning strategies you ultimately put in place will be based on your particular circumstances, it’s likely that your incapacity plan will include some, or all, of the following:
Healthcare power of attorney: An advanced directive that grants an individual of your choice the immediate legal authority to make decisions about your medical treatment in the event of your incapacity.Living will: An advanced directive that provides specific guidance about how your medical decisions should be made during your incapacity.Durable financial power of attorney: A planning document that grants an individual of your choice the immediate legal authority to make decisions related to the management of your finances, real estate, and business interests. Revocable living trust: A planning document that immediately transfers control of all assets held by the trust to a person of your choosing to be used for your benefit in the event of your incapacity. The trust can include legally binding instructions for how your care should be managed and even spell out specific conditions that must be met for you to be deemed incapacitated.
Don’t let a bad situation become much worse
You may be powerless to prevent your potential incapacity, but proper estate planning can at least give you control over how your life and assets will be managed if it does occur. Moreover, such planning can prevent your family from enduring needless trauma, conflict, and expense during this already trying time.
If you’ve yet to plan for incapacity, we can counsel you on the proper planning vehicles to put in place, and help you select the individuals best suited to make such critical decisions on your behalf. If you already have planning strategies in place, we can review your plan to make sure it’s been properly set up, maintained, and updated. Contact us today to get started.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Estate Plan Strategy Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
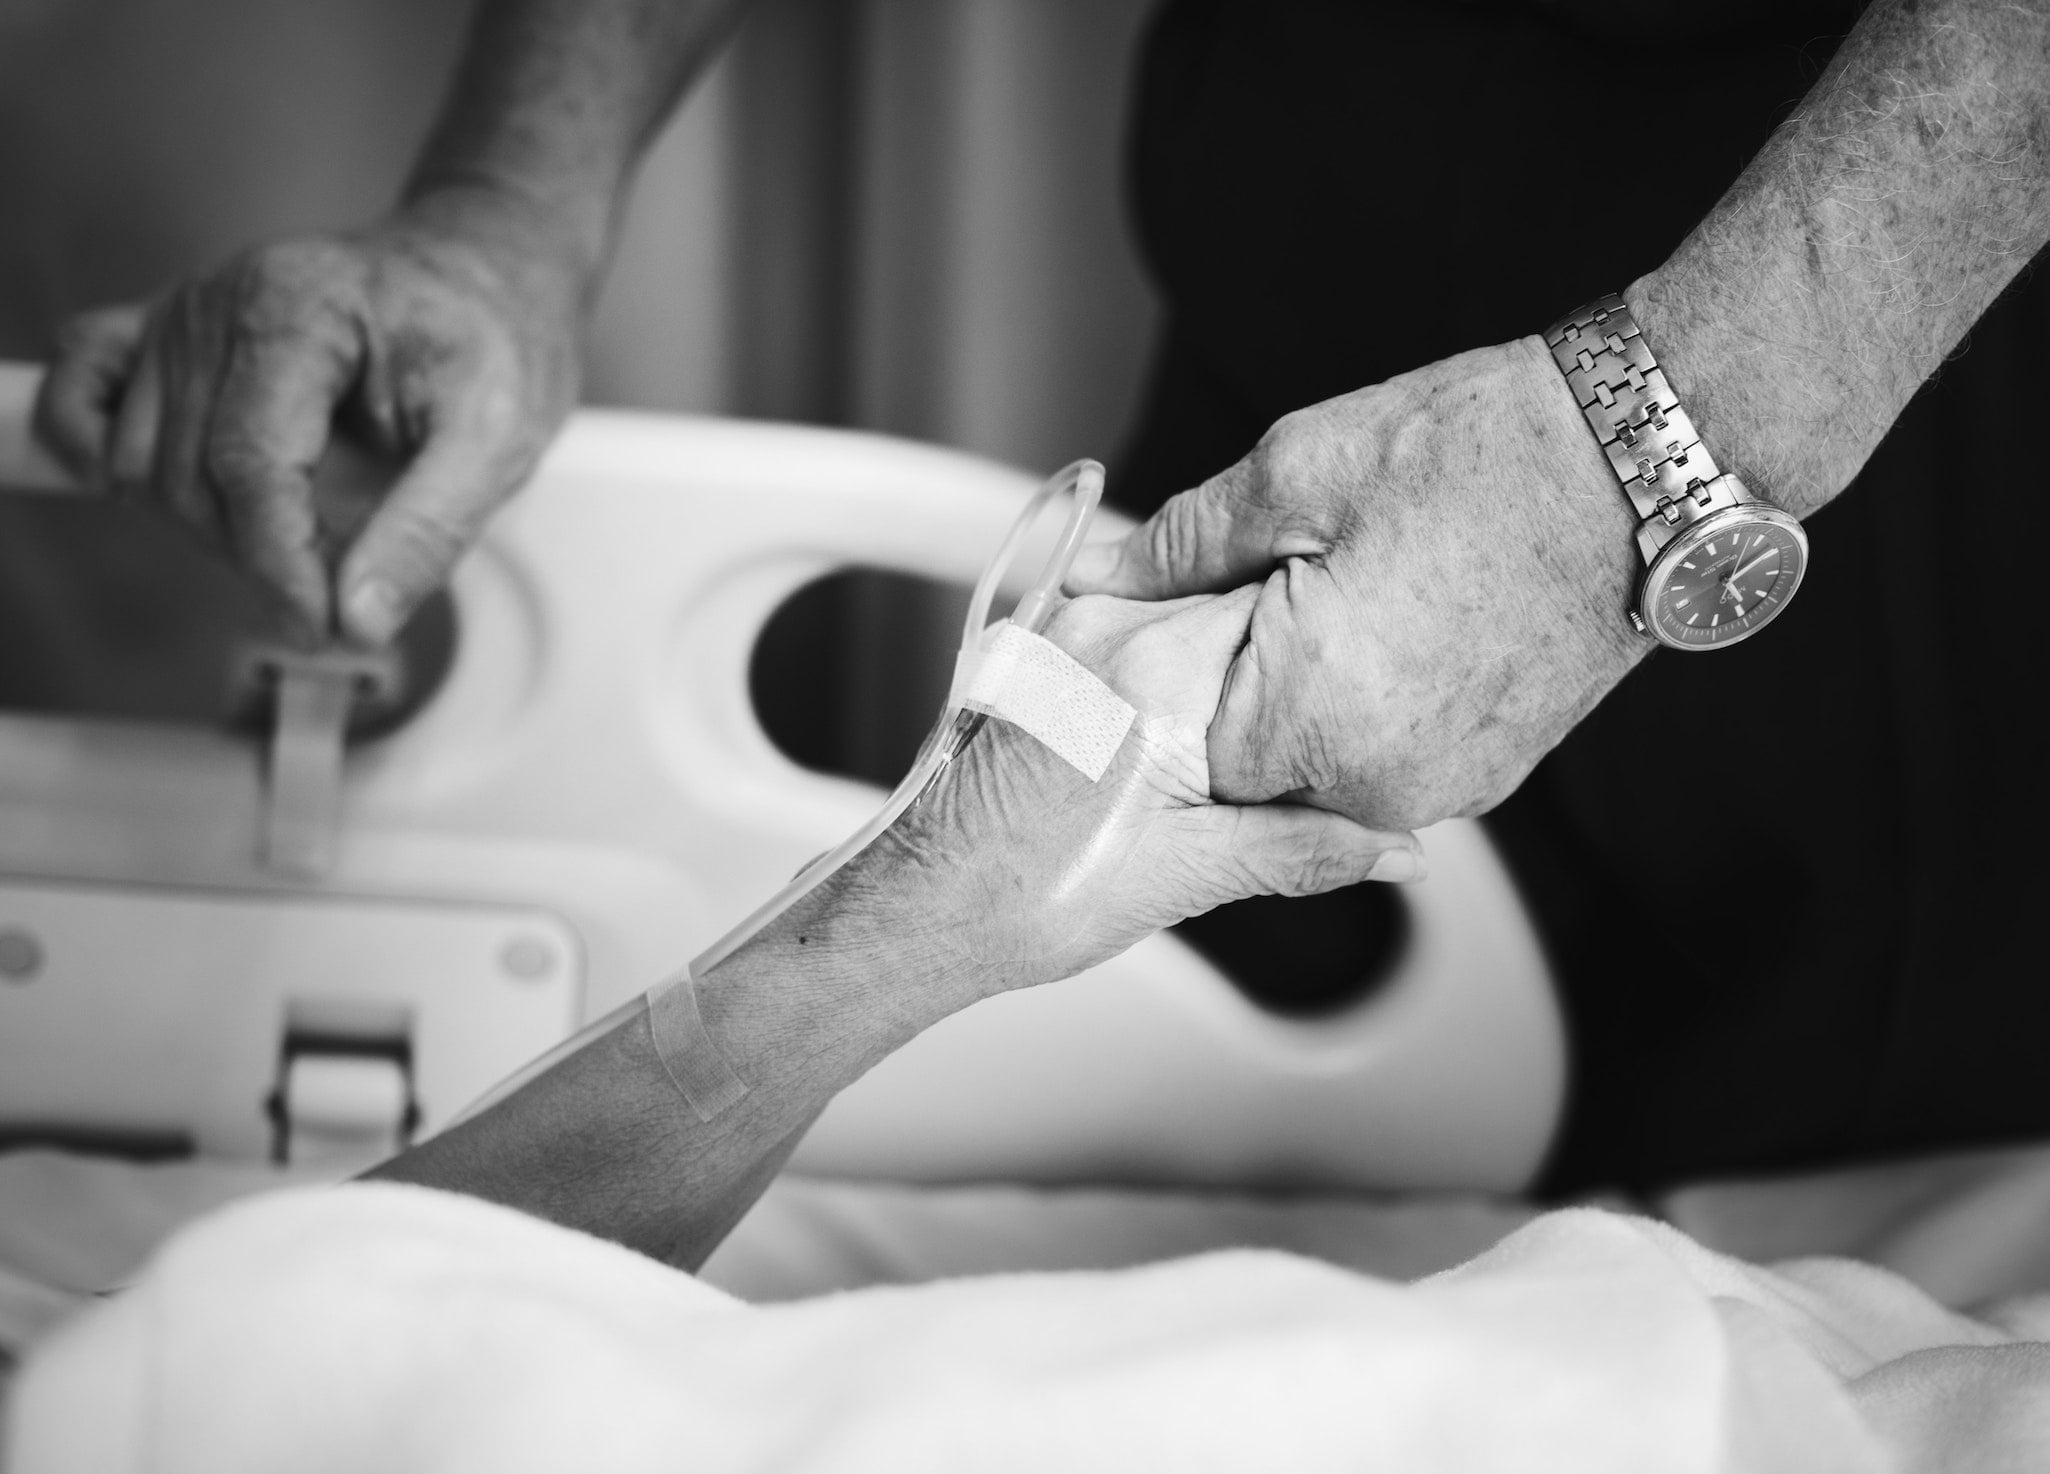
The Real Cost To Your Family: Not Planning For Incapacity
Going on vacation entails lots of planning: packing luggage, buying plane tickets, making hotel reservations, and confirming rental vehicles. But one thing many people forget to do is plan for the worst. Traveling, especially in foreign destinations, means you’ll likely be at greater risk than usual for illness, injury, and even death.In light of this reality, you must have a legally sound and updated estate plan in place before taking your next trip. If not, your loved ones can face a legal nightmare if something should happen to you while you’re away. The following are 5 critical estate planning tasks to take care of before departing.
1. Make sure your beneficiary designations are up-to-date
Some of your most valuable assets, like life insurance policies and retirement accounts, do not transfer via a will or trust. Instead, they have beneficiary designations that allow you to name the person (or persons) you’d like to inherit the asset upon your death. It’s vital you name a primary beneficiary and at least one alternate beneficiary in case the primary dies before you. Moreover, these designations must be regularly reviewed and updated, especially following major life events like marriage, divorce, and having children.
2. Create power of attorney documents
Outside of death, unforeseen illness and injury can leave you incapacitated and unable to make critical decisions about your own well-being. Given this, you must grant someone the legal authority to make those decisions on your behalf through power of attorney. You need two such documents: medical power of attorney and financial durable power of attorney. A medical power of attorney gives the person of your choice the authority to make your healthcare decisions for you, while durable financial power of attorney gives someone the authority to manage your finances. As with beneficiary designations, these decision-makers can change over time, so before you leave for vacation, be sure both documents are up to date.
3. Name guardians for you minor children
If you’re the parent of minor children, your most important planning task is to legally document guardians to care for your kids in the event of your death or incapacity. These are the people whom you trust to care for your children—and potentially raise them to adulthood—if something should happen to you. Given the monumental importance of this decision, we’ve created a comprehensive system called the Kids Protection Plan that guides you step-by-step through the process of creating the legal documents naming these guardians. You can get started with this process right now for free by visiting our user-friendly website
4. Organize your digital assets
If you’re like most people, you probably have dozens of digital accounts like email, social media, cloud storage, and cryptocurrency. If these assets aren’t properly inventoried and accounted for, they’ll likely be lost forever if something happens to you. At minimum, you should write down the location and passwords for each account, and ensure someone you trust knows what to do with these digital assets in the event of your death or incapacity. To make this process easier, consider using LastPass or a similar service that stores and organizes your passwords.
Complete your vacation planning now
If you have a vacation planned, be sure to add these 5 items to your to-do list before leaving. And if you need help completing any of these tasks—or would simply like us to double check the plan you have in place—consult with us.We recommend you complete these tasks at least 8 weeks before you depart. However, if your trip is sooner than that, call and let us know you need a rush Estate Plan Strategy Session, and we’ll do our best to fit you in as soon as possible. Contact us today to get started.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Estate Plan Strategy Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
4 Critical Estate Planning Tasks to Complete Before Going on Vacation
Selecting a beneficiary for your life insurance policy sounds pretty straightforward. But given all of the options available and the potential for unforeseen problems, it can be a more complicated decision than you might imagine.
For instance, when purchasing a life insurance policy, your primary goal is most likely to make the named beneficiary’s life better or easier in some way in the aftermath of your death. However, unless you consider all of the unique circumstances involved with your choice, you might actually end up creating additional problems for your loved ones.
Last week, we discussed the first three of six questions you should ask yourself when choosing a life insurance beneficiary. Here we cover the remaining three:
4. Are any of your beneficiaries minors?
While you’re technically allowed to name a minor as the beneficiary of your life insurance policy, it’s a bad idea to do so. Insurance carriers will not allow a minor child to receive the insurance benefits directly until they reach the age of majority—which can be as old as 21 depending on the state.If you have a minor named as your beneficiary when you die, then the proceeds would be distributed to a court-appointed custodian tasked with managing the funds, often at a financial cost to your beneficiary. And this is true even if the minor has a living parent. This means that even the child’s other living birth parent would have to go to court to be appointed as custodian if he or she wanted to manage the funds. And, in some cases, that parent would not be able to be appointed (for example, if they have poor credit), and the court would appoint a paid fiduciary to hold the funds.
Rather than naming a minor child as beneficiary, it’s better to set up a trust for your child to receive the insurance proceeds. That way, you get to choose who would manage your child’s inheritance, and how and when the insurance proceeds would be used and distributed.
5. Would the money negatively affect a beneficiary?
When considering how your insurance funds might help a beneficiary in your absence, you also need to consider how it might potentially cause harm. This is particularly true in the case of young adults. For example, think about what could go wrong if an 18 year old suddenly receives a huge windfall of cash. At best, the 18 year old might blow through the money in a short period of time. At worst, getting all that money at once could lead to actual physical harm (even death), as could be the case for someone with substance-abuse issues.To help mitigate these potential complications, some life insurance companies allow your death benefit to be paid out in installments over a period of time, giving you some control over when your beneficiary receives the money. However, as discussed earlier, if you set up a trust to receive the insurance payment, you would have total control over the conditions that must be met for proceeds to be used or distributed. For example, you could build the trust so that the insurance proceeds would be kept in trust for beneficiary’s use inside the trust, yet still keep the funds totally protected from future creditors, lawsuits, and/or divorce.
6. Is the beneficiary eligible for government benefits?
Considering how your life insurance money might negatively affect a beneficiary is absolutely critical when it comes to those with special needs. If you leave the money directly to someone with special needs, an insurance payout could disqualify your beneficiary from receiving government benefits.Under federal law, if someone with special needs receives a gift or inheritance of more than $2,000, they can be disqualified for Supplemental Security Income and Medicaid. Since life insurance proceeds are considered inheritance under the law, an individual with special needs SHOULD NEVER be named as beneficiary.
To avoid disqualifying an individual with special needs from receiving government benefits, you would create a “special needs” trust to receive the proceeds. In this way, the money will not go directly to the beneficiary upon your death, but be managed by the trustee you name and dispersed per the trust’s terms without affecting benefit eligibility. The rules governing special needs trusts are quite complicated and can vary greatly from state to state, so if you have a child who has special needs, meet with us to ensure you have the proper planning in place, not just for your insurance proceeds, but for the lifetime of care your child may need.
Make sure you’ve considered all potential circumstances
These are just a few of the questions you should consider when choosing a life insurance beneficiary. Consult with us to be certain you’ve thought through all possible circumstances.And if you think you may need to create a trust—special needs or otherwise—to receive the proceeds of your life insurance, meet with us, so we can properly review all of your assets and consider how to best leave behind what you have in a way that will create the most benefit—and the least challenges—for the people you love. Schedule your Estate Plan Strategy Session today.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Estate Plan Strategy Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.

6 Questions to Consider When Selecting Beneficiaries For Your Life Insurance Policy—Part 2
Selecting a beneficiary for your life insurance policy sounds pretty straightforward. You’re just deciding who will receive the policy’s proceeds when you die, right? But as with most things in life, it’s a bit more complicated than that. It can help to keep in mind that naming someone as your life insurance beneficiary really has nothing to do with you: It should be based on how the funds will affect the beneficiary’s life once you’re no longer here.
It’s very likely that if you’ve purchased life insurance, you did so to make someone’s life better or easier in some way in the wake of your death. But unless you consider all of the unique circumstances involved with your choice, you might actually end up creating additional problems for the people you love.
Given the potential complexities involved, here are a few important questions you should ask yourself when choosing your life insurance beneficiary:
1. What are you trying to accomplish?
The first thing to consider is the “real” reason you’re buying life insurance. On the surface, the reason may simply be because it’s the responsible thing for adults to do. But we recommend you dig deeper to discover what you ultimately intend to accomplish with your life insurance.Are you married and looking to replace your income for your spouse and kids after death? Are you single without kids and just trying to cover the costs of your funeral? Are you leaving behind money for your grandkids’ college fund? Are you intending to make sure your business continues after you’re gone? Or perhaps your life insurance is in place to cover a future estate-tax burden?The real reason you’re investing in life insurance is something only you can answer. The answer is critical, because it is what determines how much and what kind of life insurance you should have in the first place. And by first clearly understanding what you’re actually intending to accomplish with the policy, you’ll be in a much better position to make your ultimate decision—who to select as beneficiary.
2. What are your beneficiary options?
Your insurance company will ask you to name a primary beneficiary—your top choice to get the insurance money at the time of your death. If you fail to name a beneficiary, the insurance company will distribute the proceeds to your estate upon your death. If your estate is the beneficiary of your life insurance, that means a probate court judge will direct where your insurance money goes at the completion of the probate process. And this process can tie your life insurance proceeds up in court for months or even years. To keep this from happening to your loved ones, be sure to name—at the very least—one primary beneficiary.In case your primary beneficiary dies before you, you should also name at least one contingent (alternate) beneficiary. For maximum protection, you should probably name more than one contingent beneficiary in case both your primary and secondary choices have died before you. Yet, even these seemingly straightforward choices are often more complicated than they appear due to the options available.For example, you can name multiple primary beneficiaries, like your children, and have the proceeds divided among them in whatever way you wish. What’s more, the beneficiary doesn’t necessarily have to be a person. You can name a charity, nonprofit, or business as the primary (or contingent) beneficiary.
It’s important to note that if you name a minor child as a primary or contingent beneficiary (and he or she ends up receiving the policy proceeds), a legal guardian must be appointed to manage the funds until the child comes of age. This can lead to numerous complications (which we’ll discuss in detail next week in Part Two), so you should definitely consult with an experienced Family Law attorney like us if you’re considering this option.
When selecting your beneficiaries, you should ultimately base your decision on which person(s) or organization(s) you think would most benefit from the money. In general, you can designate one or more of the following examples as beneficiaries:
- One person
- Two or more people (you decide how money is split among them)
- A trust you’ve created
- Your estate
- A charity, nonprofit, or business
3. Does your state have community property laws?
If you’re married, you’ll likely choose your spouse as the primary beneficiary. But unless you live in a state with community-property laws, you can technically choose anyone: a close friend, your favorite charity, or simply the person you think needs the money most.
That said, if you do live in a community-property state, your spouse is entitled to the policy proceeds and will have to sign a form waiving his or her rights to the insurance money if you want to name someone else as beneficiary. Currently, community-property states include Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Estate Plan Strategy Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
6 Questions to Consider When Selecting Beneficiaries for a Life Insurance Policy
Being asked by a family member or close friend to serve as trustee for their trust upon their death can be an incredible honor. At the same time, however, serving as a trustee can be a massive responsibility—and the role is not for everyone. In fact, depending on the type of trust, the assets held by the trust, the specific terms of the trust, and the beneficiaries named, the job can require you to fulfill a wide range of complex (and potentially unpleasant) duties over the course of many years. What’s more, trustees are both ethically and legally required to properly execute those duties or face liability. Given this, agreeing to serve as trustee is a decision that shouldn’t be made lightly. Indeed, sometimes the best thing you can do for everyone involved is to politely decline the job. Remember, you don’t have to take it. That said, depending on who nominated you, declining to serve may not be an easy or practical option. Or you might enjoy the opportunity to be a trustee, so long as you understand what it entails.It’s best to make your decision about serving as trustee with eyes wide open. Here’s a brief look at what the job will likely entail, along with some situations where you might want to seriously think twice about agreeing.
What trustees do
As mentioned earlier, a trustee’s duties can vary tremendously depending on the size of the estate, the type of trust, and the trust’s specific instructions. That said, every trust comes with a few core requirements, primarily revolving around accounting for, managing, and distributing the trust’s assets to its named beneficiaries.
Regardless of the type of trust or the assets it holds, some of a trustee’s key responsibilities include:
- Identifying and protecting the trust assets
- Determining what the trust’s terms actually require you to do
- Managing the trust assets for the term specified and distributing them properly
- Filing income and estate taxes for the trust
- Communicating regularly with beneficiaries
- Being scrupulously honest, highly organized, and keeping detailed records
- Closing the trust when the trust terms specify
Ultimately, trustees have a fiduciary duty to properly manage the trust in the best interest of all the trust beneficiaries. Consult with us for more in-depth details regarding the duties and responsibilities a specific trust will require of you as trustee.
Can I get help?
Fortunately, you’re not expected to go it alone: Trustees are encouraged to seek assistance from outside professionals to fulfill their duties. Remember, you do NOT need experience in law, finance, or taxes to serve as trustee. And while you won’t be able to profit from the job, you are able to be paid for your role as trustee. That said, many trustees, especially family members, choose not to accept any payment beyond what’s required to cover the trust expenses. Yet, this all depends on your personal situation and relationship with the trust’s creator and beneficiaries, and of course, the nature of the assets in the trust. In either case, however, you won’t have to use your own funds to get the job done.
Signs the trustee role might be a bad idea
Given the sense of loyalty and filial responsibility that’s often involved, it might feel difficult to turn the trustee role down. But for a number of reasons, saying “no thanks” can sometimes be the best decision, not only for you, but for all parties involved. Of course, this is an entirely personal decision and one you’ll ultimately have to make for yourself after considering all of the factors. That said, here are a few red flags that can signal the role might be better fulfilled by someone other than you:
- Your job, family, and/or health situation is such that you won’t be able to give the job the time and attention it deserves. Some trusts can require far more work than others, and if the role would seriously impede your own life, you might consider declining.
- You don’t get along with the beneficiaries. If there are underlying conflicts or bad blood with the people you’ll be required to serve, this could make the job incredibly difficult and unpleasant for everyone.
- The trust’s terms are vague and/or unclear, leaving you in the position to make difficult decisions you don’t feel qualified to make. Such grey areas are especially troublesome when it comes to distributing trust assets to young adult beneficiaries, who might not be the most responsible with their spending and/or lifestyle.
- It’s not clear exactly what assets the trust creator (grantor) owned, and/or the estate is highly unorganized. Tracking down and managing unorganized and/or poorly funded assets can be a massive undertaking—and potential liability.
- Lawsuits are likely or already underway. As trustee, it’s your duty to defend the trust against lawsuits, and just doing this can be a huge expenditure of your time and energy. What’s more, if a lawsuit against the trust is successful, it could seriously reduce the trust’s value, making your job infinitely more challenging.
We can help you decide
Given the serious nature of a trustee’s responsibilities, you can meet with us for help deciding whether or not to accept the job. We can offer a clear, unbiased assessment of what will be required of you based on the specific trust’s terms, assets, and beneficiaries.And if you do decide to accept the trustee role, we can guide you step-by-step through the entire process, ensuring you effectively fulfill all of the grantor’s wishes with minimal risk. Serving as trustee can be a lot of work, but if you go into the job with eyes wide open and have the proper guidance, it can be an immensely rewarding experience. Contact us today to learn more.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Estate Plan Strategy Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
Understand What’s At Stake Before Agreeing to Serve as Trustee
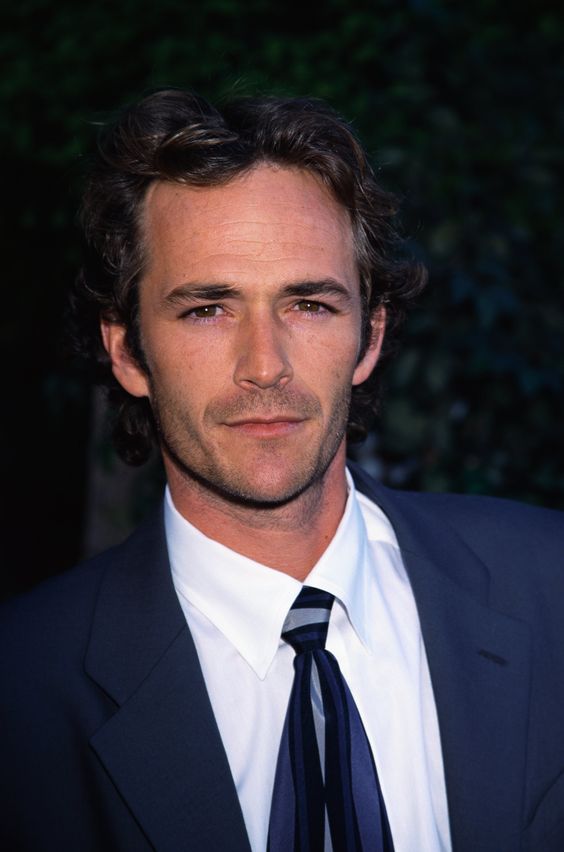
In late February, Luke Perry, who became famous starring in the 1990s TV series Beverly Hills 90210, suffered a massive stroke at age 52. He was hospitalized under heavy sedation, and five days later, when it became clear he wouldn’t recover, his family decided to remove life support.
Perry died on March 4th, 2019 surrounded by his two children—21-year-old Jack and 18-year-old Sophie—along with his fiancé, ex-wife, mother, siblings, and others.
Whether or not you were a Luke Perry fan, it’s hard not to be somewhat shocked when someone so young, successful, and seemingly healthy passes away so suddenly. In these moments, the fragile impermanence of life becomes glaringly obvious. It’s life’s way of reminding us that incapacity and death can strike at any time, no matter who you are.
Such reminders can make you feel extremely vulnerable. And they can also be a precious reminder to make the most of life now. Reminders of the fleeting nature of life can actually be a wonderful thing, if it motivates you to savor life now AND take the proper action to protect the ones you love through proper estate planning. And while we don’t yet know exactly what levels of planning Perry had in place, it appears he was thoughtful and responsible enough to have at least covered the basics.
Planning for incapacity and death
Perry was reportedly inspired to create his own estate plan following a fairly recent health scare. In 2015, after discovering he had precancerous growths during a colonoscopy, Perry created a will, leaving everything to his two children. Since Perry was worth an estimated $10 million, divorced with kids from the first marriage, and about to be married again, creating a will was the very least he could do.But wills are just a small part of the planning equation. Wills only apply to the distribution of your assets following death, and even then, your will must go through the court process known as probate for your assets to be distributed. Because a will only comes into play upon your death, if you’re ever incapacitated by accident or illness as Perry was, it offers neither you nor your family any protections.In Perry’s case, he was incapacitated by a stroke and on life support for nearly a week before he died. During this period, the fact Perry had a will was irrelevant because he was still alive. But given how events unfolded, it appears Perry had other planning vehicles in place to prepare for just this situation.
The power of life and death
During the time he was incapacitated, someone was called upon to make crucial medical decisions for Perry’s welfare, while his family was summoned to his side. To this end, it’s likely that Perry designated someone to serve as his medical decision-maker by granting them medical power of attorney. He may have also created a living will, which would provide specific instructions to this individual regarding how to make these medical decisions. Granting medical power of attorney gives the person you name the authority to make healthcare decisions on your behalf in the event of your incapacity. The document that does this is known as an advance healthcare directive, and it’s an absolute must-have for every adult over age 18. Perry was put on life support for nearly a week, and then he was removed from it and allowed to die without ever regaining consciousness—and without any apparent conflict between his loved ones. This indicates that someone in his family likely had the legal authority to make those heart-wrenching decisions over Perry’s life and death. Without medical power of attorney, if any of Perry’s family were in disagreement over how his medical care should be handled, the family may have needed a court order to terminate life support. This could have needlessly prolonged the family’s suffering and made his death even more public, costly, and traumatic for those he left behind.
The power over your money
Along with medical power of attorney, every adult should also have financial durable power of attorney. In the event of your incapacity, financial durable power of attorney is an estate planning tool that gives the person you choose immediate authority to manage your finances, such as paying your bills, collecting government benefits, and overseeing your bank accounts.
We can’t be sure at this point whether or not Perry put in place durable power of attorney, but since this planning document goes hand-in hand with medical power of attorney, it’s almost certain he did. Yet seeing that Perry was only incapacitated for five days before his death, durable power of attorney may not seem totally necessary in his case. But what if Perry’s incapacity had lasted a lot longer?Given that Perry could have lingered on life support for months or years, it’s crucial that someone he trusted had the authority to manage his finances during his incapacity. Without durable power of attorney, the court will choose someone to manage your finances, and that someone might be a person you wouldn’t want anywhere near your life savings or checkbook. What’s more, that someone could even be a “professional” who gets paid hefty hourly fees to handle things, even if you have family members who want to serve.
Learn from Perry’s example
While Perry’s death is certainly sad, if it inspires you to put the proper estate planning in place, it can ultimately prove immensely beneficial. Whether you already have a basic plan in place or nothing at all, meet with us to get educated about the specifics necessary to keep your family out of court and out conflict if and when something happens to you. We’ll help ensure that in the event of your incapacity, or when you die, your loved ones will have the same protections Perry’s had—and more. Contact us today to attend one of our live educational events or get started with a private Estate Plan Strategy Session.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Estate Plan Strategy Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
Gen-X 90210 Star Luke Perry’s Death Demonstrates the Importance of Planning for Incapacity
Like many taxpayers, if you’ve already filed your federal income taxes for 2018, you may be surprised to discover you’re not getting a refund this time. If so, this was almost certainly due to the sweeping tax overhaul made by the 2017 Tax Cut and Jobs Act (TCJA).
Since personal tax rates were lowered by the TCJA, it’s natural to assume you would owe less taxes, not more. But as you may have discovered, this isn’t always the case.
Seeing that the TCJA was promised to offer most people a tax break, understanding why you might owe more taxes in 2018 (rather than less) can be confusing. The following questions and answers are designed to shed some light on this situation, so you can start revising your tax strategies for coming years.
Q: What changed?
A: In addition to lowering personal income tax rates, the TCJA doubled the standard exemption to $12,000, added limits to deductions for state and local taxes (SALT), eliminated personal exemptions, set limits on deductions for home-mortgage interest, among many other changes. Given all of the changes, you may find that you’re no longer withholding the proper amount of taxes from your paycheck and/or quarterly installments to the IRS. When filing, this can result in either overpaying your taxes (and getting a refund) or underpaying (and owing money).
Q: What does this mean for me?
A: In light of these new changes, you should carefully review your withholding and make adjustments if necessary. To help with this, the IRS published new withholding tables and updated its withholding calculator into which you can input your current tax data to see if you need to make any changes.
Q: How do I change my withholding?
A: If you work as an employee, you change your withholding by making adjustments to your W-4. If you work for yourself, you either increase or decrease your estimated quarterly payments. A W-4 determines how much income tax is withheld from your pay by your employer. You fill out a W-4 when you start a new job, but you can change it at any time. Specifically, the form asks you for the number of allowances you want to claim based on personal factors, such as being married and/or having children and filing as head of household.
The more allowances you claim, the less federal income tax your employer will withhold, which translates to more money in your paycheck. The fewer allowances you claim, the more federal income tax your employer will withhold, lowering your take-home pay.
It’s important that you withhold the proper amount from your paycheck or make quarterly payments. Don’t withhold enough, and you’ll owe the IRS at the end of the year. Withhold too much, and you might get a big refund, but you’ve basically given the government an interest-free loan for that year.
Maximize your tax savings
Adjusting your withholding is just one of many strategies you can use to save on your taxes. Indeed, the TCJA also changed tax laws that have the potential to affect your estate planning strategies as well. In light of this, when the 2018 tax season wraps up, we’ll be pairing up with one of our favorite local CPAs to bring you support and guidance that you can use to maximize your tax savings in 2019 and beyond. Contact us to learn more.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Estate Plan Strategy Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.
Why You Might Actually Owe Taxes in 2018
Even if you put a totally solid estate plan in place, it can end up proving worthless if it’s not properly updated. Estate planning is not a one-and-done type of deal: It should continuously evolve along with your life circumstances.No matter who you are, your life will inevitably change: families change, laws change, assets change, and goals change. In the absence of any major life events, we recommend reviewing your plan annually to make sure its terms are up to date.Yet there are several common life events that require you to immediately update your plan—that is, if you want it to actually work and keep your loved ones out of court and out of conflict. To this end, if any of the following seven events occur, contact us right away.
1. You get married
Marriage not only changes your relationship status, it changes your legal status. Regardless of whether it’s your first marriage or fifth, you must take the proper steps to ensure your plan properly reflects your current wishes and needs. After getting hitched, some of your most pressing concerns include: naming your new spouse as a beneficiary on your insurance policies and retirement accounts, granting him or her medical power of attorney and/or durable power of attorney (if that’s your wish), and adding him or her to your will and/or trust.
2. You get divorced
Since divorce can be so overwhelming, estate planning often gets overshadowed by the other dramatic new changes happening. But failing to update your plan for divorce can have devastating consequences. Once divorce proceedings start, you’ll need to ensure your future ex is no longer eligible to receive any of your assets or make financial and medical decisions on your behalf—unless that’s your wish. Once the divorce is finalized and your property is divided, you’ll need to adjust your planning to match your new asset profile and living situation.
3. You give birth or adopt
Welcoming a new addition to your family can be a joyous occasion, but it also demands entirely new levels of planning and responsibility. At the top of your to-do list should be legally naming both long and short-term guardians for your child. Our Kids Protection Plan offers everything you need to complete this process for free right now. Once you’ve named guardians, consider putting planning vehicles, such as trusts, in place for your kids. These documents can make certain the assets you want your child to inherit will be passed on in the most effective and beneficial way possible for everyone involved. Consult with us to learn which planning strategies are best suited for your family.
4. A loved one dies
The death of a family member, partner, or close friend can have major consequences for both your life and estate plan. If the person was included in your plan, you need to update it accordingly to fill any gaps his or her absence creates. From naming new beneficiaries, executors, and guardians to identifying new heirs to receive assets allocated to the deceased, make sure you address all voids the death creates as soon as possible.
5. You get seriously ill or injured
As with death, illness and injury are an unavoidable part of being human. If you’ve been diagnosed with a serious illness or are involved in a life-changing accident, you may want to review the people you’ve chosen to handle your healthcare decisions as well as how those decisions should be made. The person you want as your healthcare proxy can change with time, so be sure your plan reflects your current wishes.
6. You relocate to a new state
Since estate planning laws can vary widely from state to state, if you move to a different state, you’ll need to review and/or revise your plan to comply with your new home’s legal requirements. Some of these laws can be super complex, so consult with us to make sure your plan will still work exactly as you desire in your new location.
7. Your assets or liabilities change significantly
Whenever your estate’s value dramatically increases or decreases, you should revisit your plan to ensure it still offers the maximum protection and benefits for yourself and your loved ones. Whether you inherit a fortune, take out a new loan, close your business, or change your investment portfolio, your plan should be adjusted accordingly.
Count on us for guidance and support
You can count on us to ensure your estate plan is regularly reviewed and updated at all times. In fact, we have built-in processes to make sure this happens—be sure to ask us about them. What’s more, rather than looking at the process as yet another task you have to accomplish, we view an annual review as a meaningful ritual that lets you see where your family has been and where you plan to go. But however you look at it, a regular review will put you at ease, knowing your family is protected and provided for no matter what happens.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Estate Plan Strategy Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.

7 Events That Necessitate a Review of Your Estate Plan
Unlike most of your assets, individual retirement accounts (IRAs) do not pass to your family through a will. Instead, upon your death, your IRA will pass directly to the people you named via your IRA beneficiary designation form.Unless you take extra steps, the named beneficiary can do whatever he or she wants with the account’s funds once you’re gone. The beneficiary could cash out some or all of the IRA and spend it, invest the funds in other securities, or leave the money in the IRA for as long as possible.For a number of reasons that we’ll address more below, you might not want your heirs to receive your retirement savings all at once. One way to prevent this is to designate your IRA into a trust. But you can’t just use any trust to hold an IRA; you’ll need to set up a special type of revocable trust specifically designed to act as the beneficiary of your IRA upon your death. Such a trust is referred to by different names—IRA Living Trust, IRA Inheritor’s Trust, IRA Stretch Trust—but for this article, we’re simply going to call it an IRA Trust.IRA Trusts offer a number of valuable benefits to both you and your beneficiaries. If you have significant assets invested through one or more IRA accounts, you might want to consider the following advantages of adding an IRA Trust to your estate plan.
1. Protection from creditors, lawsuits, & divorce
While IRAs are typically protected from creditors while you’re alive, once you die and the funds pass to your beneficiaries, the IRA can lose its protected status when your beneficiary distributes the funds to him or herself. One way to counteract this is to leave your retirement assets through an IRA Trust, in which case your IRA funds will be shielded from creditors as long as they remain in the trust.IRA Trusts are also useful if you’re in a second (or more) marriage and want your IRA assets to be used for the benefit of your surviving spouse while he or she is living, and then to distributed or be held for the benefit of your children from a prior marriage after your surviving spouse passes. This would ensure that your surviving spouse cannot divert retirement assets to a new spouse, to his or her children from a prior marriage, or lose them to a creditor before the funds ultimately get to your children.
2. Protection from the beneficiary’s own bad behavior
In addition to outside creditors, an IRA Trust can also help protect the beneficiary from his or her own poor money-management skills and spending habits. If the IRA passes to your beneficiary directly, there’s nothing stopping him or her from quickly blowing through the wealth you’ve worked your whole life to build.
When you create an IRA Trust, however, you can add restrictions to the trust’s terms that control when the money is distributed as well as how it is to be spent. For example, you might stipulate that the beneficiary can only access the funds at a certain age or upon the completion of college. Or you might stipulate that the assets can only be used for healthcare needs or a home purchase. With our support, you can get as creative as you want with the trust’s terms.
3. Tax savings
One of the primary benefits of traditional IRAs is that they offer a period of tax-deferred growth, or tax-free growth in the case of a Roth IRA. Yet if the IRA passes directly to your beneficiary at your death and is immediately cashed out, the beneficiary can lose out on potentially massive tax savings. Not only will the beneficiary have to pay taxes on the total amount of the IRA in the year it was withdrawn, but he or she will also lose the ability to “stretch out” the required minimum distributions (RMDs) over their life expectancy.A properly drafted IRA Trust can ensure the IRA funds are not all withdrawn at once and the RMDs are stretched out over the beneficiary’s lifetime. Depending on the age of the beneficiary, this gives the IRA years—potentially even decades—of additional tax-deferred or tax-free growth.
4. Minors
If you want to name a minor child as the beneficiary of your IRA, they can’t inherit the account until they reach the age of majority. So without a trust, you’ll have to name a guardian or conservator to manage the IRA until the child comes of age.When the beneficiary reaches the age of majority, he or she can withdraw all of the IRA funds at once—and as we’ve seen, this can have serious disadvantages. With an IRA Trust, however, you name a trustee to handle the IRA management until the child comes of age. At that point, the IRA Trust’s terms can stipulate how and when the funds are distributed. Or the terms can even ensure the funds are held for the lifetime of your beneficiary, to be invested by your beneficiary through the trust.
Find out if an IRA Trust is right for you
While IRA Trusts can have major benefits, they’re not the best option for everyone. Laws regarding IRA Trusts vary widely from state to state, so in some places, they’ll be more effective than others. Plus, the value of IRA Trusts also varies greatly depending on your specific family situation, so not everyone will want to put these trusts in place.
If you have more than $150,000 in retirement accounts, consult with us to find out if an IRA Trust is the most suitable option for passing on your retirement savings to benefit your family.
Proper estate planning can keep your family out of conflict, out of court, and out of the public eye. If you’re ready to create a comprehensive estate plan, contact us to schedule your Estate Plan Strategy Session. Even if you already have a plan in place, we will review it and help you bring it up to date to avoid heartache for your family. Schedule online today.